Home loans in Adelaide
from a local mortgage broker

Our office is on Prospect Road, not in another state. We compare 60+ lenders and handle the South Australian grants and HomeStart questions that national call centres get wrong.

Adelaide, from an Adelaide office

The numbers that matter before you pick a broker.
0
Lenders on our panel
0
Loan products we can compare
0
Application, not six
0
Cost to you for arranging your finance
We are paid a commission by the lender when a loan settles, and that is disclosed to you in writing before you commit. Lender and government fees can still apply and are set out in your loan documents.

Why use an Adelaide broker rather than a national one?

Home loan policy is national. Grants, stamp duty and the lender that only lends here are not.

We are in Prospect, not a call centre

1/132 Prospect Rd
You can meet us. The office is five minutes from Prospect Road’s cafe strip and about ten minutes from the CBD, and we work across the inner north and the wider metro area: Prospect, Nailsworth, Sefton Park, Enfield, Walkerville, North Adelaide, Norwood, Unley, Gilberton, Broadview, Croydon Park and Bowden, and out to Mawson Lakes, Golden Grove, Modbury and Glenelg.

We know the South Australian schemes

FHOG, stamp duty, HomeStart
South Australia runs its own first home owner grant, its own stamp duty rules and its own government-backed lender. An interstate broker will not know how those interact with a lender’s policy, and the difference shows up in what you can actually borrow.

We speak your language

English and Persian
Kourosh works with a large part of Adelaide’s Persian-speaking community, and a home loan is a bad place to be guessing at unfamiliar terminology. If English is your second language, you can have the whole conversation in Persian and read the documents in English with someone explaining them.

Who we help in Adelaide

Six situations where the lender you apply to changes the answer more than the rate does.

First home buyers

South Australia has one of the more generous first home packages in the country, and it changes depending on whether you buy new or established. The grant, the stamp duty position and the federal deposit guarantee are three separate things with three separate applications, and missing one of them is the most expensive mistake a first home buyer makes here.

Self-employed and contractors

If your income is a distribution, a trust, retained profits or two years of variable BAS figures, the answer you get depends almost entirely on which lender reads it. Some will use one year of financials. Some add back depreciation and one-off expenses. Some will not look at you at all. The work is in knowing which is which before an application is lodged.

Refinancing and equity release

If your loan has been sitting with the same lender for a few years, the rate you are on is usually not the rate that lender offers new customers. Refinancing is also how most people fund a renovation, consolidate other debt or release equity for the next purchase. Whether it is worth doing depends on your break costs, your LVR and how long you plan to keep the property, not on the headline rate. If you are in Adelaide, our refinance home loan in Adelaide page works through the South Australian costs.

Doctors, dentists and allied health

Some lenders treat medical and allied health professionals differently on deposit and on lenders mortgage insurance, and the eligible occupation list is not the same at every lender. Whether you qualify depends on your registration and your lender, not on the profession alone. Our medico home loans in Adelaide page goes through it in detail. Nurses and midwives have their own home loans for nurses in Adelaide page, and other allied health roles have their own allied health home loans in Adelaide page.

Building and renovating

A construction loan draws down in stages against the builder’s progress payments, so the approval, the valuation and the cash flow all work differently to a standard purchase. It is also the loan type most often held up by paperwork that could have been sorted at the start.

Buying an investment property

Buying to invest changes the lending questions. How rental income is assessed, how existing debt is treated, and how the structure affects what you can borrow next time all vary by lender, so they are worth settling before you make an offer.
Whichever of these you are in, the useful conversation is the same one: what your income actually looks like on paper, what deposit you have, and which lenders read that combination favourably. Our borrowing power calculator will give you a rough starting figure before you speak to anyone.

New or established? In South Australia it changes everything

The one decision that moves more money than the interest rate does for a first home buyer here.
Buying or building NEWBuying an ESTABLISHED home
First Home Owner GrantAvailable to eligible first home ownersNot available. The SA grant is for new homes only
Stamp duty reliefFull relief for eligible first home buyers, applied for separatelyStandard duty applies, with no first home buyer relief
Value capsNone for contracts signed on or after 6 June 2024Not relevant, as no grant or duty relief applies
HomeStart FinanceCan be used with eitherCan be used with either
Loan typeOften a construction loan drawn in stagesStandard purchase, single drawdown
Timing riskBuild delays affect drawdowns and rate locksSettlement date is usually fixed
The grant and the stamp duty relief apply to eligible first home buyers only, and both depend on your contract date. Contracts signed before 6 June 2024 were capped. Contracts signed on or after that date are not. We still check your eligibility against RevenueSA with you before you sign anything.

South Australian grants, in plain terms

What is actually on offer here, and the part most guides get wrong.
RevenueSA administers a first home owner grant of up to $15,000 for eligible first home owners buying or building a new residential property in South Australia that will be their principal place of residence. Separate stamp duty relief exists for eligible first home buyers, with its own application. For contracts entered into on or after 6 June 2024, RevenueSA applies no property value cap to either, and the stamp duty relief on an eligible new home, or on vacant land to build one, is full relief.
Plenty of South Australian pages still quote the old caps, which only apply to contracts signed before 6 June 2024. The rule that catches people now is ownership. For contracts from 13 February 2025, you are not eligible for the grant if you, or your spouse or domestic partner, own or have ever owned residential property in Australia. Check the current rules on RevenueSA’s first home owner grant page before you sign, and we will go through them with you.
Two other things worth knowing. The grant and the stamp duty relief are separate applications and you can qualify for one without the other. And HomeStart Finance is a South Australian government-backed lender with low deposit and shared equity products that the major banks do not offer, which is worth understanding even where it is not the right answer for you.

What to bring to the first appointment

Bring these and we can tell you what you can borrow in the first conversation rather than the third.

Proof of who you are

Driver licence or passport, and Medicare card. If you are not an Australian citizen, your visa grant notice as well.

Proof of what you earn

Employees: two recent payslips. Self-employed: two years of tax returns and notices of assessment, or recent BAS if your lender will use them. Add rental statements or Centrelink letters if they apply.

Proof of what you owe

Three to six months of statements for your everyday account, plus limits and balances for credit cards, car loans, buy now pay later and HECS or HELP.

Proof of your deposit

Statements showing the savings and where they came from. If part of it is a gift, a short letter from the person giving it. Most lenders want to see genuine savings history.
Do not have all of it? Come anyway. Half the value of the first meeting is working out which of these actually matters for your situation, and there is no cost either way.

How it works

Three steps, and no cost to you for arranging the finance.

1

Talk it through, 30 minutes

In person on Prospect Road, or by phone or video if that is easier. We work out what you are buying, what your income looks like on paper, and which grants and schemes you may be eligible for. Nothing is submitted anywhere at this stage and there is no cost.

2

We check the panel, not just one bank

We match your circumstances to the lenders whose policy actually fits them, then show you the options side by side with what each one means for your repayments and your flexibility later. You choose, not us.

3

Application, approval and settlement

We prepare and lodge the application, deal with the lender’s questions, and coordinate with your conveyancer and, if it applies, with RevenueSA for the grant. We keep you updated at each step through to settlement, and we are still here afterwards.

Suburbs we work across

All of metropolitan Adelaide, plus the Hills and the south coast.

Inner north

Prospect, Nailsworth, Sefton Park, Broadview, Enfield, Kilburn, Blair Athol, Collinswood, Walkerville, Medindie, Gilberton, North Adelaide

East and inner south

Norwood, Kensington, Payneham, St Peters, Unley, Malvern, Mitcham, Glenside, Burnside, Magill

West and coast

Woodville, Findon, Athol Park, Fulham, Henley Beach, Grange, West Lakes, Semaphore, Port Adelaide, Glenelg, Somerton Park, Brighton

North and outer

Mawson Lakes, Golden Grove, Modbury, Redwood Park, Salisbury, Elizabeth, Gawler, Munno Para, Tea Tree Gully

South

Marion, Oaklands Park, Morphett Vale, Aberfoyle Park, Happy Valley, Noarlunga, Seaford, Aldinga, Hallett Cove

Hills and beyond

Stirling, Aldgate, Lenswood, Mount Barker, Littlehampton, Nairne, Strathalbyn, Victor Harbor, Goolwa
Your lender does not care which suburb our office is in, and neither should you. What a local broker knows that a national one does not is how South Australian grants, stamp duty and HomeStart interact with a lender’s policy.
Testimonials

This is why you should let us handle your business finance

Posted on Google Google
Morteza Rayati profile picture
Morteza Rayati
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
I had a very good experience with Loanity and definitely recommend them. One thing I really like about Loanity is that they help you actually understand the whole loan process, rather than just telling you what to do. Their website also has several useful tools and information that you can use even before becoming their client, which I found very helpful when trying to understand my options. A special thanks to Kourosh. He genuinely puts time and effort into answering your questions and making sure you understand everything properly. Whenever I had questions, he took the time to explain things clearly and go through the different options with me, rather than just giving a quick answer. For me, this level of transparency, education and support makes a big difference. You feel that you are involved in the process and understand what is happening, rather than just handing everything over to a broker. Really appreciate Kourosh and the Loanity team for their time, effort and professional service. Highly recommended.
Posted on Google Google
mojgan profile picture
mojgan
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
I had great experience,They are very knowledgeable and professional through all the process,Highly recommend . Thank you so much 😊
Posted on Google Google
Siavash Farhadi profile picture
Siavash Farhadi
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Working with Kourosh and his team on my unsecured personal loan for debt consolidation was a seamless experience from start to finish. As a top-tier finance broker, Kourosh took care of the entire loan comparison process to deliver a truly tailored financial solution aligned with my budget. His communication was prompt, the application process was hassle-free, and the quick turnaround time led to a fast approval with no hidden fees. Even after comparing options with multiple brokers, Kourosh secured the most competitive low interest rate and flexible repayment terms on the market. For anyone in need of expert financial advice and reliable service, I highly recommend Kourosh and his team
Posted on Google Google
Arezo Valandizi profile picture
Arezo Valandizi
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
I’m very grateful to Kourosh and the Lonity team for all their help, advice, and support throughout my home loan journey. Kourosh has been incredibly patient, professional, and supportive. He always takes the time to explain everything clearly, answer all my questions, and guide me through every step of the process. His advice has given me confidence and made the whole experience much easier and less stressful. I truly appreciate all the time and effort Kourosh has put into helping me achieve my goal of buying my own home. I highly recommend Kourosh and the Lonity team to anyone looking for a knowledgeable, trustworthy, and genuinely supportive mortgage broker. Thank you so much, Kourosh, for all your help and support.
Posted on Google Google
Sheema profile picture
Sheema
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
We had a fantastic experience working with Kourosh Tabandeh. He went above and beyond to help us increase our borrowing capacity for our home purchase, and we are truly grateful for all his support. Kourosh is extremely professional, knowledgeable, caring, and dedicated. He was always available to answer our questions, followed up on everything carefully, and genuinely did his best to achieve the best possible outcome for us. Buying a home can be a stressful process, but having Kourosh by our side made a huge difference. We really appreciated his patience, persistence, and the genuine care he showed throughout the whole process. We highly recommend Kourosh to anyone looking for a trustworthy, professional, and supportive mortgage broker. Thank you so much, Kourosh, for everything you did for us!
Posted on Google Google
Hassan Khaleghi Sohi profile picture
Hassan Khaleghi Sohi
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Excellent service and a very professional experience. I had a phone consultation regarding my finance and refinancing options, and I was very impressed with the consultant’s knowledge, professionalism and helpful advice. Everything was explained clearly and I never felt pressured. Highly recommended for anyone looking for professional and reliable financial services.
Posted on Google Google
hadi yousefi profile picture
hadi yousefi
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Excellent service from Loanity! Professional, knowledgeable, and always available when needed. They made the whole loan process smooth and stress-free, and went above and beyond to get the best outcome for me. Highly recommend Loanity to anyone looking for a reliable and trustworthy mortgage broker. Fantastic service!
Posted on Google Google
Buff Ryder profile picture
Buff Ryder
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
⭐⭐⭐⭐⭐ I couldn’t be happier with the service I received from Kia. Refinancing can feel like a complicated and stressful process, but Kia made everything so easy from start to finish. Kia was always friendly, approachable and happy to answer any questions I had. They took the time to understand what I was looking for, explained everything clearly, and kept me updated throughout the whole process. What really stood out was how much Kia genuinely cared about getting the best outcome for me. They went above and beyond, and I always felt like I was in good hands. I’m very grateful for all Kia’s help and would happily recommend Kia to my family and friends. Thank you, Kia, for making the refinancing process such a smooth and positive experience! Ps: He is really hard working as well.

Beyond the Reviews: Hear From Our Clients

Every home loan journey is different, and choosing the right mortgage broker is a big decision. Hear directly from Loanity clients as they share their real experiences working with our team. Watch their stories and discover what it’s like to have Loanity by your side throughout the home loan process.

Come and see us in Prospect

We work with clients across Adelaide, including Prospect, Collinswood, Sefton Park, North Adelaide, Walkerville, Norwood, Port Adelaide, West Lakes, Henley Beach, Somerton Park and Oaklands Park, and right across the metro area.
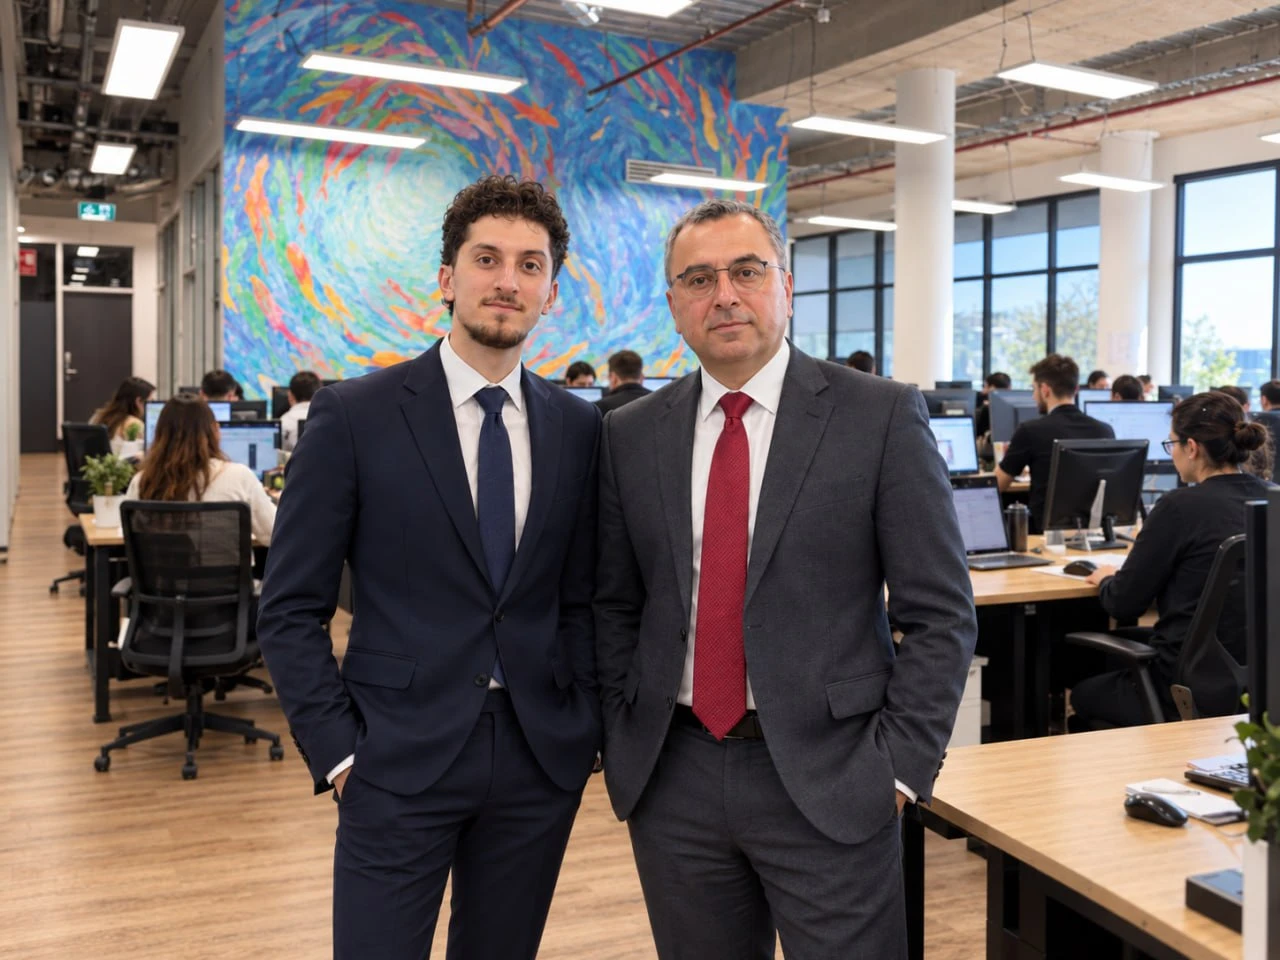
The Loanity team at the Prospect Road office in Adelaide

Call us on

1800 237 537

1/132 Prospect Rd
Prospect SA 5082

Mon to Fri 9:00am to 5:00pm
Sat 9:00am to 3:00pm, Sunday closed

We compare the lender panel for you

0
We compare 60 lenders on our panel
0
Scan through over 260 loan options 
0
Our fees disclosed up front*
0
3 shortlisted options, presented to you
Judo Bank logo
Capify logo
Banjo logo
Angle Finance logo
Wisr logo
Shift logo
Plenti logo
Pepper Money logo
NOW Finance logo
Latitude logo
Lumi logo
Moula logo
Lenders available through our panel. Availability depends on the asset, the amount and your circumstances.

Other things we handle

In Adelaide specifically, our medico home loans in Adelaide page covers doctors, dentists and allied health, and equipment finance in Adelaide covers machinery, vehicles and fit-outs for local businesses. Beyond that, if your question is not a standard home loan, it is probably one of these. Refinancing an existing loan covers rate reviews, equity release and debt consolidation. First home buyer loans covers the national picture on deposits and guarantees. Professional home loan packages covers the national medico picture. Construction loans covers building and major renovation.
On the business side, our business loan page covers working capital and cash flow. If you would rather start with numbers, the loan repayment calculator and the refinance calculator are free to use.

How we work: when the first assessment is not the final word

A Loanity client example. Details are generalised and the story is shared with the client’s consent.

The situation
A first home buyer couple with a small deposit and a dependent child was told by another broker that their borrowing capacity was too low.

Our approach
We checked their real, documented expenses, reviewed every existing debt and limit, and compared lender policies for first home buyers before choosing one. We then structured the loan around their priorities.

Result
A borrowing capacity $70,000 higher than the first assessment.

This example is not an Adelaide purchase. It is here to show how we assess an application.

Important information: this is one client’s experience. Results depend on each person’s circumstances and a lender’s credit assessment, and are not typical. General information only, not financial or credit advice.
If a lender or another broker has told you your borrowing capacity is too low, a second assessment against different lender policies is worth asking for before you change your plans. You can book a free consultation or check your own numbers first with the borrowing power calculator.
Still got questions?

Adelaide home loan questions, answered

Does a mortgage broker in Adelaide cost me anything?

In most cases no. We are paid a commission by the lender when the loan settles, and that is disclosed to you in writing before you commit to anything. Lender and government fees such as application, valuation and settlement charges can still apply and are set out in your loan documents.

No. Plenty of clients do the whole thing by phone, email and video, and we can meet at the office at 1/132 Prospect Rd if you would rather sit down with someone. Being local matters less for convenience than it does for knowing the South Australian rules.

RevenueSA administers a one-off payment of up to $15,000 for eligible first home owners buying or building a new residential property in South Australia that will be their principal place of residence. It does not apply to established homes, or to vacant land on its own. For contracts entered into on or after 6 June 2024 there is no property value cap. For contracts from 13 February 2025, you are not eligible if you, or your spouse or domestic partner, own or have owned residential property in Australia. Check RevenueSA for the current rules before you sign, and we will confirm it with you.

No, they are two separate concessions with two separate applications, and the criteria are similar but not identical. You can qualify for one without qualifying for the other, which is why they should be checked individually rather than assumed together.

HomeStart is a South Australian government-backed lender offering low deposit and shared equity products that the major banks generally do not. It suits some borrowers very well and is the wrong answer for others, and that depends on your deposit, your income and how long you plan to hold the property. It is worth understanding either way.

Usually yes, and the lender matters more than anything else. Lenders differ on how many years of financials they want, whether they will use one year, and what they add back to your income. Some will consider BAS or accountant-prepared figures. The work is matching your paperwork to a lender whose policy reads it favourably before an application goes in.

It depends on the lender, the property and whether you are eligible for a government guarantee scheme. Below a certain deposit level most lenders require lenders mortgage insurance, which is a real cost that some schemes and some professional packages avoid. We will tell you where you sit before you start looking at properties.

All of metropolitan Adelaide. We are based in Prospect, so we see a lot of the inner north, Nailsworth, Sefton Park, Enfield, Walkerville and North Adelaide, but the lender does not care where our office is and neither should you if the advice is right.

It varies by lender and by how complete your documents are, and it is the lender’s decision rather than ours. What we can control is not sending an application to a lender whose policy was never going to fit, because a decline sits on your credit file and makes the next application harder.

Yes. Kourosh works with a large part of Adelaide’s Persian-speaking community and the whole conversation can happen in Persian. The loan documents themselves are in English, and we will go through them with you rather than leave you to guess.

Talk to an Adelaide broker

A free 30 minute conversation, no obligation, and no cost from us for arranging your finance. Call 1800 237 537 or book a time that suits you.

Important information about this page

Broker services are provided at no cost to you in most cases, as we are paid a commission by the lender. Lender and government fees may apply and are set out in your loan documents. Eligibility, terms and rates vary by lender and by individual circumstances and are subject to change.
This page is general information only. It does not take your objectives, financial situation or needs into account, and it is not tax or legal advice. Grant and stamp duty eligibility is determined by RevenueSA under the rules applying to your contract date, not by us. Loanity is a credit representative and can provide credit assistance once we understand your circumstances. Green Idea Pty Ltd, Credit Representative Number 576678, is an authorised representative of Red Rock Brokers Group Pty Ltd, Australian Credit Licence 405961.