Equipment finance broker
for Australian businesses

One application, a panel of 60+ lenders, and a structure that matches how long you actually intend to keep the asset.

Primary, secondary or tertiary? The tier that sets your rate

The single label that decides your rate, your term and whether you get approved at all.
Every equipment lender in Australia sorts assets into three tiers, and almost none of them explain it to you. The tier is decided by one question: if the loan went bad tomorrow, how easily could the lender sell the asset and get its money back? That answer sets your pricing before anyone has looked at your business.

Primary assets

The tier lenders are most comfortable with, so pricing and terms are usually better here than on the other two
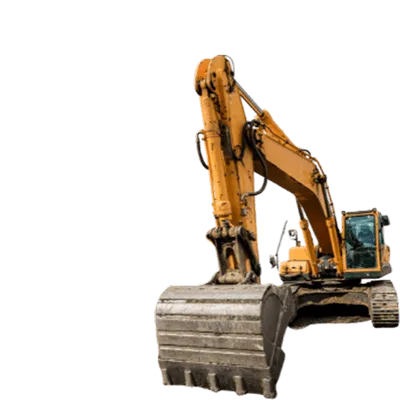
Trucks, prime movers, trailers, excavators and other earth-moving plant. These hold their resale value and a lender can move them quickly if it ever has to, so they attract the sharpest pricing and the most relaxed conditions on the market.

Secondary assets

Good rates, a few more conditions
Medical and dental equipment, food production plant, manufacturing machinery, commercial kitchen fit-outs. There is a real resale market, but it is thinner than for a truck, so expect slightly firmer pricing and a closer look at your trading history.

Tertiary assets

Fewer lenders, and the panel matters most
Point-of-sale systems, IT hardware and software, fit-out and signage, older specialised machinery. Resale value is low or close to nil, so many lenders simply decline. This is the tier where going to one bank gets you a no and the right panel gets you a yes.
Two businesses with identical financials can be quoted very differently on the same day purely because one is buying a tipper and the other is buying a point-of-sale fit-out. Knowing your tier before you apply is what stops you accepting the first offer you are given, or assuming a knock-back from your own bank means nobody will fund it. If you want a rough repayment figure before you speak to anyone, our asset finance calculator will do the arithmetic on a term and a balloon.

Chattel mortgage, hire purchase, lease or rental?

Four structures, four different answers at tax time and at the end of the term.
Most businesses that overpay on equipment finance do not overpay because they were given a bad rate. They overpay because the structure did not match how long they intended to keep the asset. Ownership is the fork in the road: it decides who claims the depreciation, who claims the GST, and what happens on the last day of the term.

Chattel mortgage

You own it from day one
You take ownership immediately and the lender takes a mortgage over the asset as security. Because you are the legal owner, you claim depreciation and the interest portion of each repayment, and the GST on the purchase price is claimable in your next BAS. A balloon at the end lowers the monthly payment. This is the most common structure for Australian businesses buying equipment they intend to keep.

Commercial hire purchase

You own it at the final payment
The lender buys the asset and hires it to you, and title passes to you once the last payment is made. The tax position is close to a chattel mortgage, but ownership is deferred, which makes it a little less flexible if you want to sell or refinance part-way through the term.

Finance lease

The lender owns it, you use it
The lender buys the asset and leases it to you, usually for two to five years, and keeps legal ownership throughout. At the end you generally choose between buying it for the agreed residual, refinancing that residual, or handing it back. Lease payments are deductible as a business expense rather than through depreciation.

Operating lease and rental

Use it, then hand it back
Closest to a straight rental. It suits assets you will replace before they wear out, which in practice usually means IT hardware and some vehicles. You never own the asset, so you are paying for use rather than building equity in it.
StructureWho owns itWhat you claimGST on purchaseBest suited to
Chattel mortgageYou, from day oneDepreciation + interestClaim up front in your next BASKeeping the asset
Commercial hire purchaseYou, at the last paymentDepreciation + interestTreatment follows ownershipHold to term
Finance leaseThe lenderLease payments deductibleHandled by the lenderResidual strategy
Operating lease / rentalThe lenderRental payments deductibleHandled by the lenderReplacing before wear-out
Which structure leaves your business better off depends on your entity, your turnover and how you are taxed, so the choice belongs to you and your accountant. What we do is make sure the finance side can actually deliver the structure the two of you land on, and that the lenders we approach are ones that write it.

What equipment can you finance?

(Hint: almost everything!)

Vehicles & utes

(or anything else that has wheels…)
Work utes, vans, EVs, trucks, fleet vehicles.
Business owner reviewing equipment finance options

Machinery & heavy equipment

Excavators, forklifts, bobcats, earthmoving tools, cranes.
Loanity finance broker at work

Medical & dental equipment

Chairs, scanners, imaging units, diagnostic tools.
Machinery on a worksite

Hospitality and retail fit-outs

Coffee machines, ovens, fridges, POS systems, shop furniture.
Commercial vehicle being financed

Technology & IT equipment

Servers, monitors, laptops, printers, security systems.
Business equipment in use

Industrial & manufacturing

CNC machines, packaging equipment, production-line tech.
Loanity team member
Zero obligation…just free guidance!

We compare the lender panel for you

0
We compare 60 lenders on our panel
0
Scan through over 260 loan options 
0
Our fees disclosed up front*
0
3 shortlisted options, presented to you
Judo Bank logo
Capify logo
Banjo logo
Angle Finance logo
Wisr logo
Shift logo
Plenti logo
Pepper Money logo
NOW Finance logo
Latitude logo
Lumi logo
Moula logo
Lenders available through our panel. Availability depends on the asset, the amount and your circumstances.
The big benefits

Why most businesses finance 
rather than pay cash

52 - Loanity

Protect your cash flow

Keep your money working on hiring, marketing, stock and growth instead of tying it up in equipment.
53 - Loanity

Built for businesses that move fast

If your business moves fast, your finance should too. Some deals settle in a couple of days, though timing is the lender’s decision and depends on the asset, the documents and your circumstances.
54 - Loanity

Better tax outcomes

Depending on the structure, repayments or depreciation may be tax-deductible.*
55 - Loanity

Own it or lease it

Chattel mortgage, finance lease, hire purchase or rental, so the structure fits your business.
004 - Loanity

Secured against the asset

Because the asset itself is the security, equipment finance is usually priced differently to unsecured lending, and the asset tier drives how many lenders will look at it.
56 - Loanity

Grow without the waiting

Get the equipment today… use it to earn tomorrow. Scale your business without slowing down.
Zero obligation…just free guidance!

Instant asset write-off: where it stands for equipment now

On 12 May 2026, as part of the 2026-27 Budget, the Government announced it would permanently set the small business instant asset write-off at $20,000 from 1 July 2026 for businesses with an aggregated turnover under $10 million. That measure is now law, which ends more than a decade of the threshold being extended one year at a time.
Two details decide whether a purchase actually qualifies, and both catch people out. The asset has to be first used or installed ready for use within the income year, so an order placed or paid for before 30 June but delivered in July belongs to the following year. And the deduction is only available where your business owns the asset, which means the structure you choose determines your eligibility before the calendar does.
We are finance brokers, not tax agents, so treat this as background rather than advice and confirm your own position with your accountant and against the ATO guidance on the $20,000 instant asset write-off.

Low doc, a new ABN, or buying used?

The situations where a broker earns their keep and a single bank gives you a single answer.

Light on paperwork

Not every lender wants two years of financials before it will look at a $60,000 machine. Low doc and streamlined asset finance exists for exactly this, usually against a clean credit file and an asset the lender is comfortable with. The trade-off is priced in, and it is worth knowing what that trade-off is before you accept it.

A newer ABN

A young ABN is not automatically a no. It narrows the panel and it puts more weight on the asset tier, the deposit and whether you have industry experience behind you. The mistake is applying to your own bank first, collecting a decline, and carrying that enquiry into every application after it.

Used and private sale

Second-hand equipment is financed every day in Australia, and buying used is often the smarter commercial call. Age caps vary by lender and by asset tier, and a private sale is handled differently from a dealer purchase, so the question is which lender, not whether it is possible.
Every credit enquiry leaves a mark on your file. Applying to the lender most likely to say yes, rather than working down the list until someone does, is the practical reason businesses use a broker for equipment finance rather than going direct.
Buying in Adelaide? Our equipment loans adelaide page is the one to read: it covers the local lender panel and the suburbs we work across. If the purchase sits alongside a wider funding need, our business loan broker page covers working capital, cash flow and debt consolidation.

How it works with Loanity

30-minute
strategy call

We understand what you need, when you need it, and how to structure the finance so it doesn’t choke your cashflow.

1

We compare 60+ lenders & put the options side by side

No fluff. No confusing jargon. Just equipment finance options matched to your business, compared side by side.

2

Approval, then
settlement
Once approved, you take delivery, start working, and start earning. We handle the paperwork, negotiations, settlement.

3

1

30-minute equipment strategy call

We work out what you are buying, how long you will keep it, and which structure fits your cash flow.

2

We compare the lender panel for your asset

We match your asset tier and trading history to the lenders most likely to approve it, then put the options side by side.

3

Approval, then settlement

Once you choose an option we manage the application through to settlement and keep you updated at each step.
Zero obligation…just free guidance!
What our clients say

Why businesses work with us

Posted on Google Google
Morteza Rayati profile picture
Morteza Rayati
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
I had a very good experience with Loanity and definitely recommend them. One thing I really like about Loanity is that they help you actually understand the whole loan process, rather than just telling you what to do. Their website also has several useful tools and information that you can use even before becoming their client, which I found very helpful when trying to understand my options. A special thanks to Kourosh. He genuinely puts time and effort into answering your questions and making sure you understand everything properly. Whenever I had questions, he took the time to explain things clearly and go through the different options with me, rather than just giving a quick answer. For me, this level of transparency, education and support makes a big difference. You feel that you are involved in the process and understand what is happening, rather than just handing everything over to a broker. Really appreciate Kourosh and the Loanity team for their time, effort and professional service. Highly recommended.
Posted on Google Google
mojgan profile picture
mojgan
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
I had great experience,They are very knowledgeable and professional through all the process,Highly recommend . Thank you so much 😊
Posted on Google Google
Siavash Farhadi profile picture
Siavash Farhadi
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Working with Kourosh and his team on my unsecured personal loan for debt consolidation was a seamless experience from start to finish. As a top-tier finance broker, Kourosh took care of the entire loan comparison process to deliver a truly tailored financial solution aligned with my budget. His communication was prompt, the application process was hassle-free, and the quick turnaround time led to a fast approval with no hidden fees. Even after comparing options with multiple brokers, Kourosh secured the most competitive low interest rate and flexible repayment terms on the market. For anyone in need of expert financial advice and reliable service, I highly recommend Kourosh and his team
Posted on Google Google
Arezo Valandizi profile picture
Arezo Valandizi
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
I’m very grateful to Kourosh and the Lonity team for all their help, advice, and support throughout my home loan journey. Kourosh has been incredibly patient, professional, and supportive. He always takes the time to explain everything clearly, answer all my questions, and guide me through every step of the process. His advice has given me confidence and made the whole experience much easier and less stressful. I truly appreciate all the time and effort Kourosh has put into helping me achieve my goal of buying my own home. I highly recommend Kourosh and the Lonity team to anyone looking for a knowledgeable, trustworthy, and genuinely supportive mortgage broker. Thank you so much, Kourosh, for all your help and support.
Posted on Google Google
Sheema profile picture
Sheema
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
We had a fantastic experience working with Kourosh Tabandeh. He went above and beyond to help us increase our borrowing capacity for our home purchase, and we are truly grateful for all his support. Kourosh is extremely professional, knowledgeable, caring, and dedicated. He was always available to answer our questions, followed up on everything carefully, and genuinely did his best to achieve the best possible outcome for us. Buying a home can be a stressful process, but having Kourosh by our side made a huge difference. We really appreciated his patience, persistence, and the genuine care he showed throughout the whole process. We highly recommend Kourosh to anyone looking for a trustworthy, professional, and supportive mortgage broker. Thank you so much, Kourosh, for everything you did for us!
Posted on Google Google
Hassan Khaleghi Sohi profile picture
Hassan Khaleghi Sohi
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Excellent service and a very professional experience. I had a phone consultation regarding my finance and refinancing options, and I was very impressed with the consultant’s knowledge, professionalism and helpful advice. Everything was explained clearly and I never felt pressured. Highly recommended for anyone looking for professional and reliable financial services.
Posted on Google Google
hadi yousefi profile picture
hadi yousefi
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Excellent service from Loanity! Professional, knowledgeable, and always available when needed. They made the whole loan process smooth and stress-free, and went above and beyond to get the best outcome for me. Highly recommend Loanity to anyone looking for a reliable and trustworthy mortgage broker. Fantastic service!
Posted on Google Google
Buff Ryder profile picture
Buff Ryder
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
⭐⭐⭐⭐⭐ I couldn’t be happier with the service I received from Kia. Refinancing can feel like a complicated and stressful process, but Kia made everything so easy from start to finish. Kia was always friendly, approachable and happy to answer any questions I had. They took the time to understand what I was looking for, explained everything clearly, and kept me updated throughout the whole process. What really stood out was how much Kia genuinely cared about getting the best outcome for me. They went above and beyond, and I always felt like I was in good hands. I’m very grateful for all Kia’s help and would happily recommend Kia to my family and friends. Thank you, Kia, for making the refinancing process such a smooth and positive experience! Ps: He is really hard working as well.
Still got questions?

Equipment finance questions, answered

What types of assets can I finance for my business?

You can finance almost any physical asset used for business purposes, including passenger vehicles, heavy machinery, medical equipment, kitchen fit-outs, and IT hardware. Whether you are a tradie needing a new ute or a medical clinic upgrading diagnostic tools, Loanity has access to specialised lenders for both standard and niche business equipment.

A Chattel Mortgage allows you to own the asset from day one, with the lender taking a mortgage over it as security. This is popular for businesses wanting to claim GST and depreciation upfront. A Finance Lease involves the lender purchasing the asset and leasing it to you for a monthly fee. Loanity will help you compare these structures to see which best aligns with your accountant’s advice.

Only where the asset itself qualifies, and the threshold is the part people miss. The instant asset write-off applies to eligible assets costing less than $20,000, for small businesses with an aggregated turnover under $10 million, and it is claimed in the year the asset is first used or installed ready for use. Most of the machinery on this page costs well above that, in which case normal depreciation rules apply instead. The structure matters too: the deduction is only available where your business owns the asset, so a chattel mortgage or hire purchase can qualify and a lease generally cannot. We are not tax agents, so confirm your own position with your accountant.

Not necessarily. Loanity offers “Low Doc” asset finance options where you may only need to provide an ABN and recent bank statements to prove your business turnover. These products are designed for busy business owners who need to upgrade equipment quickly without the delay of preparing full financial statements or tax returns.

Asset finance is often faster than a standard business loan, because the equipment itself serves as security. Turnaround varies by lender, by asset tier and by how complete your documents are, so we will give you a realistic timeframe once we know what you are buying. Once the documents are signed, some lenders can settle quickly and pay the supplier direct. Settlement timing is the lender’s decision, not ours.

You can finance both new and used equipment through Loanity. While some banks have strict rules on the age of the asset at the end of the loan term, we work with a wide range of lenders who are flexible with older machinery or specialised used equipment, provided it is in good working order and has a clear title.

Lenders grade assets by how easily they could be resold. Primary assets such as trucks, trailers and earth-moving plant hold their value and attract the best pricing. Secondary assets such as medical, manufacturing and hospitality equipment have a thinner resale market and slightly firmer terms. Tertiary assets such as point-of-sale systems, IT hardware and fit-out have little resale value, so far fewer lenders will fund them and the panel you apply through matters more than anything else.

Often, yes. A decline from one bank reflects that bank’s credit appetite for your asset type and your trading history, not the whole market. Specialist equipment lenders write business that the major banks will not, particularly on secondary and tertiary assets. The important thing is to stop applying one at a time, because every enquiry is recorded on your credit file.

Not always. Many businesses finance the full purchase price, and whether a deposit is required depends on the asset tier, the age of the asset, how long your ABN has been trading and your credit history. Where a deposit is asked for, it is usually because it moves the application into a better lender or a better structure rather than because the lender needs the cash.

Yes, though it is handled differently. A private sale needs extra verification of the seller and the asset, and not every lender writes them. It is worth telling us it is a private sale at the start, because it changes which lenders we approach rather than whether the purchase can be funded.

A balloon is a lump sum left at the end of the term, which lowers the repayments along the way. It is useful for protecting cash flow, but it is not free money: you still owe it, and at the end you either pay it, refinance it or sell the asset. The right balloon is the one that matches how long you will realistically keep the equipment.

Stop waiting.
Just do it now.

No fee from us for arranging your finance. No obligation. A free consult and handy resources. No strings attached.
Important information about this page

Broker services are provided at no cost to you in most cases, as we are paid a commission by the lender. Lender and government fees such as establishment, PPSR and account-keeping charges may apply and are set out in your loan documents. Eligibility, terms, residual requirements and rates vary by lender, by asset and by individual circumstances, and are subject to change. Rates and product availability are current as at 1 September 2026. Confirm with us before relying on any figure on this page.

Lenders shown are those available through our panel. Displaying a lender does not mean every product from that lender is available to every applicant.

This page is general information only and is not tax advice. It does not take your objectives, financial situation or needs into account. Tax treatment, effective life and deductibility depend on your circumstances, and your accountant or registered tax agent is the right person to confirm them. Finance taken wholly for business purposes is generally not regulated by the National Credit Code, so the protections that apply to consumer credit may not apply. Loanity is a credit representative and can provide credit assistance once we understand your circumstances.