Equipment finance in Adelaide,
without the bank runaround

From a ute for a Gawler sparky to a bottling line in the Barossa. We compare 60+ lenders and bring you three structures that suit your cashflow.

60+Lenders compared

260+Loan products

What Adelaide businesses are financing

(Hint: if it earns you money, it can usually be financed)
Most searches for equipment finance in Adelaide turn up a national lender’s landing page written for nobody in particular. We are a local equipment finance broker. Adelaide and regional South Australia is the whole of our patch, and we arrange equipment loans, machinery finance and asset finance from an office on Prospect Road. If your business trades nationally, our national equipment and asset finance page covers the same ground without the local detail.

Utes, vans and fleet

(anything with wheels and an ABN behind it)
Work utes, trade vans, EVs, trucks and small fleets for Adelaide trades and couriers.

Machinery and
heavy equipment

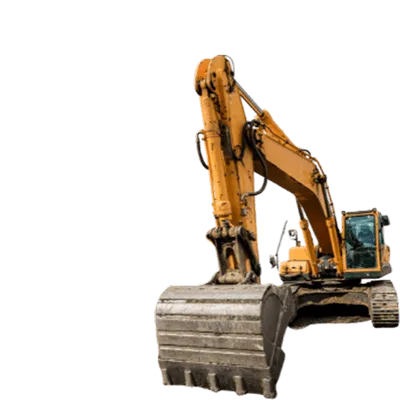
Excavators, forklifts, skid steers (bobcats), cranes and earthmoving gear for civil and construction work.
Excavator financed for a South Australian civil contractor

Medical and dental fit-outs

Chairs, imaging units, sterilisers and diagnostic gear for clinics across Adelaide.
Dental chair financed for an Adelaide clinic fit-out

Hospitality and retail fit-outs

Ovens, cool rooms, coffee machines, POS systems and shop furniture for East End and Norwood venues.
Commercial coffee machine financed for an Adelaide cafe fit-out

Technology and IT

Servers, workstations, printers, network and security systems.
Business IT hardware financed for an Adelaide office

Farm and industrial

Headers, air seeders, silos, CNC machines and production-line equipment.
CNC manufacturing equipment financed for a South Australian workshop
No cost to talk, and no obligation to proceed.
Local, not generic

Built for the industries South Australia runs on

A national lender sees an asset and a number. We see the season you buy in, the month the money comes back, and the repayment shape that suits it.

Viticulture and wine

Barossa, McLaren Vale and Clare Valley. Crushers, presses, tanks, bottling lines and vineyard tractors. Income arrives once a year, so we look for lenders who allow seasonal or structured repayments rather than flat monthly.

Broadacre and livestock

Yorke Peninsula, Eyre Peninsula and the Mid North. Headers, air seeders, boom sprays, augers and silos. Many lenders will time the first repayment to land after harvest rather than at settlement.

Defence and advanced manufacturing

Osborne, Edinburgh Parks and Tonsley. CNC machining centres, inspection and metrology equipment, robotics and automation cells. Contract-backed revenue often supports a longer term than a lender first offers.

Construction and civil

Excavators, skid steers, tippers, elevated work platforms and attachments. Because the machine secures the loan, pricing is usually sharper than an unsecured business loan for the same amount.

Health and dental practices

Adelaide CBD, North Adelaide and Prospect. Chairs, OPG and CBCT imaging, sterilisers and practice fit-outs. A fit-out is often several suppliers at once, which is easier to fund as one structured facility than five separate ones.

Hospitality and retail

East End, The Parade at Norwood, Glenelg and the suburban strips. Combi ovens, cool rooms, espresso machines, POS and joinery. Trade is seasonal here too, so the repayment shape matters as much as the rate.
We know the seasons here. Tell us yours.

Equipment loans and machinery finance from 60+ lenders

0
Lenders on our panel
0
Scan through over 260 loan options
0
Zero hidden fees, as it should be*
0
Options, shown side by side
*Loanity charges you no fee for arranging equipment finance. We are paid a commission by the lender. Lender and government fees such as establishment, PPSR and account-keeping charges still apply and are set out in your loan documents.
Judo Bank logo
Capify logo
Banjo logo
Angle Finance logo
Wisr logo
Shift logo
Plenti logo
Pepper Money logo
NOW Finance logo
Latitude logo
Lumi logo
Moula logo
*Loanity charges you no fee for arranging equipment finance. We are paid a commission by the lender, and we will tell you what that is before you sign anything. Lender and government fees such as establishment, PPSR and account-keeping charges still apply and are set out in your loan documents.

What your equipment really costs after tax

Two businesses can buy the same machine for the same price and end up paying very different amounts for it. The difference is not the finance. It is how the tax rules treat who owns the asset.

The sticker price is rarely the real cost. Under a chattel mortgage the business usually owns the asset from day one. That ownership is what unlocks the treatment: the GST on the purchase price may be claimable in your next BAS, and interest and depreciation may be deductible over the life of the loan. A finance lease works differently again, with the lease payments themselves generally treated as the deduction.

Where the business owns the asset, the instant asset write-off may also let you deduct the cost in the year the equipment is first used or installed ready for use, even though it is financed. That does not apply under a lease or a rental, because the lender owns the asset. The limit and the eligibility rules change from year to year, so check the current position on the ATO instant asset write-off page rather than a figure quoted on a broker website.

Which one leaves you better off depends on your structure, your turnover and your accountant’s view. Eligibility and treatment vary, so confirm your own position with your tax professional before you commit.

Chattel mortgage, lease or hire purchase

Three ways to hold the same machine. None of them is better in the abstract, only better for a particular set of books.

Chattel mortgage

You own the asset from day one and the lender holds security over it. It sits on your balance sheet. Commonly chosen by businesses registered for GST that want to claim the GST upfront and depreciate the asset. Most popular structure for utes, excavators and farm machinery.

Finance lease

The lender buys the equipment and leases it to you for a fixed monthly payment, with a residual at the end. Often chosen where the business wants predictable payments and plans to refresh the equipment rather than keep it. Common for IT, kitchen equipment and short-life assets.

Hire purchase and rental

With hire purchase the lender owns the asset until the final payment, then title transfers to you. Before 1 July 2012, GST rules pushed many cash-basis businesses toward chattel mortgages instead. For agreements from that date, a GST-registered business can generally claim the GST credit upfront under hire purchase as well, so the choice now comes down to ownership timing and your accountant’s preference. Rental keeps the asset off your books entirely and is usually the most flexible if the equipment is only needed for a project or a season.

What a lender actually looks at

Every lender weighs these differently, which is exactly why comparing them is worth doing. Knowing the list in advance also means you can fix the weak spot before you apply, rather than collecting a decline first.

How long the ABN has traded

Two years of trading opens the widest set of lenders. Under that, the field narrows but does not close, especially where the director has industry history or property behind them. If you are close to a milestone, waiting a few weeks can genuinely change the offers.

The asset itself

Lenders sort equipment into tiers. A late-model ute or excavator with an active resale market is easy. Highly specialised gear with a thin second-hand market is harder, because if things go wrong the lender has to sell it. Age at the end of the term matters more than age today.

Your credit file, and how you have used it

Under comprehensive credit reporting, lenders see repayment history month by month, not just defaults. They also see every application you have made. Shopping your deal around five lenders yourself leaves five enquiries on the file and makes the sixth one nervous. That is the main practical reason to go through one broker.

Whether you own property

Property ownership is not required, but most lenders price a property-owning director more keenly than a non-owner. Worth knowing, because it is often the single line that separates two very different quotes on the same machine.

Who is selling it to you

A dealer invoice is the simplest path. A private sale, a clearing sale or an interstate purchase adds a PPSR check and sometimes an inspection. All of it is doable, it just changes which lenders are in play and how long settlement takes, so it is better raised at the start than discovered on the day.

Whether the repayment fits the season

This is the one most South Australian applications get wrong. A grower or a winery does not earn evenly across twelve months, and a flat monthly repayment written for a metro business can strangle a good operation in the wrong quarter. Structured, seasonal and deferred first repayments all exist. They are just not offered unless someone asks.
Nothing above is a promise of approval. Every application is assessed by the lender on its own merits and subject to their credit criteria.
The big benefits

Why Adelaide businesses use a broker instead of their bank

Icon representing protected business cash flow

Keep your working capital

Cash stays available for wages, stock and the next job, instead of sitting inside a machine.
Icon representing fast equipment finance approval

Fast turnaround

Because the asset is the security, many equipment finance approvals come back within one to two business days. Timing depends on the lender and your paperwork.
Icon representing loan structure options

Structure chosen for your books

Chattel mortgage, lease, hire purchase or rental. We work to your accountant’s preference rather than whatever one bank happens to sell.*
*Which structures and lenders are available depends on the asset, the term and your circumstances.
Icon representing new and used equipment

New or used, dealer or private

Banks often refuse older machinery or private sales. Specialist lenders on our panel will consider both, subject to condition and clear title.
Icon representing asset secured pricing

Secured pricing, low doc options

Because the equipment secures the loan, pricing is generally sharper than unsecured lending. Some lenders will assess on ABN and bank statements alone.
Icon representing a local Adelaide broker

We are in Adelaide too

Our office is on Prospect Road. You can sit down with the person handling your file instead of a call centre in another state.
*Tax treatment depends on your circumstances. Confirm your own position with your accountant before choosing a structure.

How it works with Loanity

1

30-minute strategy call

We work out what the asset is, when you need it, and how to structure the finance so it does not choke your cashflow.

2

We compare 60+ lenders

No jargon. You get three options side by side, with the rate, the term, the fees and the residual all in plain English.

3

Settlement and delivery

We handle the paperwork, deal with the supplier and manage settlement. You take delivery and put the equipment to work.
Most of the work is ours, not yours.

Where we arrange equipment finance across South Australia

The office is in Prospect and most of our work is metropolitan Adelaide, but equipment finance does not stop at the tollgate. Documents are signed electronically and settlements are handled by phone and email, so where the machine lives matters far less than what it is and who is buying it.

Metropolitan Adelaide

Prospect, Adelaide CBD, North Adelaide, Norwood, Mile End, Port Adelaide, Salisbury, Elizabeth, Gawler, Modbury, Lonsdale, Edwardstown, Glenelg and the surrounding councils. Close enough that we can meet you at the yard if that is easier than a phone call.

Wine regions

Barossa Valley, McLaren Vale, Clare Valley, Adelaide Hills, Langhorne Creek, Coonawarra and the Riverland. Vintage decides everything here. A repayment schedule written for a business with even monthly income is the wrong shape, and we say so to the lender rather than leaving you to manage the gap.

Cropping and grazing country

Yorke Peninsula, Eyre Peninsula, the Mid North around Clare and Blyth, the Murray Mallee, the Limestone Coast and the Fleurieu. Machinery is often bought months before it earns anything. The question we ask a lender is when the first repayment should land, not just what the rate is.

Your local equipment finance broker in Adelaide

Loanity, 1/132 Prospect Rd, Prospect SA 5082
Phone 1800 237 537

We work with businesses right across greater Adelaide, including Prospect, Gawler, Elizabeth, Salisbury, Port Adelaide, Norwood, Mile End, Lonsdale and Mount Barker, as well as regional South Australia.

Equipment is rarely the only thing on the list. The same conversation can cover business loans for working capital and low rate car loans for the vehicles that are not tools of trade. If you would rather write than call, contact our Prospect office and we will come back to you.
The Loanity team at the Prospect Road office in Adelaide

Call us on

1800 237 537

1/132 Prospect Rd
Prospect SA 5082

Mon to Fri 9:00am to 5:00pm
Sat 9:00am to 3:00pm, Sunday closed

Testimonials

What our clients say

Posted on Google Google
Morteza Rayati profile picture
Morteza Rayati
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
I had a very good experience with Loanity and definitely recommend them. One thing I really like about Loanity is that they help you actually understand the whole loan process, rather than just telling you what to do. Their website also has several useful tools and information that you can use even before becoming their client, which I found very helpful when trying to understand my options. A special thanks to Kourosh. He genuinely puts time and effort into answering your questions and making sure you understand everything properly. Whenever I had questions, he took the time to explain things clearly and go through the different options with me, rather than just giving a quick answer. For me, this level of transparency, education and support makes a big difference. You feel that you are involved in the process and understand what is happening, rather than just handing everything over to a broker. Really appreciate Kourosh and the Loanity team for their time, effort and professional service. Highly recommended.
Posted on Google Google
mojgan profile picture
mojgan
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
I had great experience,They are very knowledgeable and professional through all the process,Highly recommend . Thank you so much 😊
Posted on Google Google
Siavash Farhadi profile picture
Siavash Farhadi
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Working with Kourosh and his team on my unsecured personal loan for debt consolidation was a seamless experience from start to finish. As a top-tier finance broker, Kourosh took care of the entire loan comparison process to deliver a truly tailored financial solution aligned with my budget. His communication was prompt, the application process was hassle-free, and the quick turnaround time led to a fast approval with no hidden fees. Even after comparing options with multiple brokers, Kourosh secured the most competitive low interest rate and flexible repayment terms on the market. For anyone in need of expert financial advice and reliable service, I highly recommend Kourosh and his team
Posted on Google Google
Arezo Valandizi profile picture
Arezo Valandizi
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
I’m very grateful to Kourosh and the Lonity team for all their help, advice, and support throughout my home loan journey. Kourosh has been incredibly patient, professional, and supportive. He always takes the time to explain everything clearly, answer all my questions, and guide me through every step of the process. His advice has given me confidence and made the whole experience much easier and less stressful. I truly appreciate all the time and effort Kourosh has put into helping me achieve my goal of buying my own home. I highly recommend Kourosh and the Lonity team to anyone looking for a knowledgeable, trustworthy, and genuinely supportive mortgage broker. Thank you so much, Kourosh, for all your help and support.
Posted on Google Google
Sheema profile picture
Sheema
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
We had a fantastic experience working with Kourosh Tabandeh. He went above and beyond to help us increase our borrowing capacity for our home purchase, and we are truly grateful for all his support. Kourosh is extremely professional, knowledgeable, caring, and dedicated. He was always available to answer our questions, followed up on everything carefully, and genuinely did his best to achieve the best possible outcome for us. Buying a home can be a stressful process, but having Kourosh by our side made a huge difference. We really appreciated his patience, persistence, and the genuine care he showed throughout the whole process. We highly recommend Kourosh to anyone looking for a trustworthy, professional, and supportive mortgage broker. Thank you so much, Kourosh, for everything you did for us!
Posted on Google Google
Hassan Khaleghi Sohi profile picture
Hassan Khaleghi Sohi
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Excellent service and a very professional experience. I had a phone consultation regarding my finance and refinancing options, and I was very impressed with the consultant’s knowledge, professionalism and helpful advice. Everything was explained clearly and I never felt pressured. Highly recommended for anyone looking for professional and reliable financial services.
Posted on Google Google
hadi yousefi profile picture
hadi yousefi
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Excellent service from Loanity! Professional, knowledgeable, and always available when needed. They made the whole loan process smooth and stress-free, and went above and beyond to get the best outcome for me. Highly recommend Loanity to anyone looking for a reliable and trustworthy mortgage broker. Fantastic service!
Posted on Google Google
Buff Ryder profile picture
Buff Ryder
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
⭐⭐⭐⭐⭐ I couldn’t be happier with the service I received from Kia. Refinancing can feel like a complicated and stressful process, but Kia made everything so easy from start to finish. Kia was always friendly, approachable and happy to answer any questions I had. They took the time to understand what I was looking for, explained everything clearly, and kept me updated throughout the whole process. What really stood out was how much Kia genuinely cared about getting the best outcome for me. They went above and beyond, and I always felt like I was in good hands. I’m very grateful for all Kia’s help and would happily recommend Kia to my family and friends. Thank you, Kia, for making the refinancing process such a smooth and positive experience! Ps: He is really hard working as well.
Reviews shown are from Loanity clients. Individual outcomes depend on your circumstances and lender assessment.
Still got questions?

Questions Adelaide business owners ask us

Can I get equipment finance in Adelaide if my business is under two years old?

Often yes. Several lenders on our panel will consider a newer ABN where the director has industry experience or a property asset behind them, particularly when the equipment itself is strong security. Terms are usually tighter than for an established business, so it is worth talking through your position before you apply anywhere, because multiple declined applications leave marks on your credit file.

Low doc options exist for asset finance, where a lender may assess on your ABN, GST registration and recent bank statements rather than full financials. Availability depends on the amount, the asset and your credit history, and all lending is still subject to the lender being satisfied you can meet the repayments.

Used equipment is financed regularly, and for a lot of South Australian trades and farms it is the sensible buy. Lenders generally look at the age of the asset at the end of the loan term rather than today, so a well-maintained machine with a clear title and a reasonable service history is usually workable. Very old or highly specialised gear narrows the field of lenders rather than ruling it out.

Because the equipment provides the security, asset finance usually moves faster than a standard business loan, and many approvals come back within one to two business days. The timing sits with the lender rather than with us, and it depends on how complete your documents are and how straightforward the asset is. We will tell you upfront which lenders are quick on your type of deal.

Private sales are possible with a smaller group of lenders. Expect an extra step or two: a PPSR check to confirm nothing is owing on the asset, and sometimes an independent inspection or valuation. Buying at a clearing sale or from another operator is common in farming and civil work, so it is a well-trodden path even though not every lender offers it.

A balloon or residual is a lump sum left at the end of the term. It lowers your monthly repayment but the amount still has to be dealt with, usually by paying it out, refinancing it, or selling or trading the asset. The risk to watch is the residual being higher than what the equipment is worth on the day, so we size it against realistic resale values rather than pushing the monthly figure as low as it will go.

Ready to move
on that machine?

No fee from us for arranging your finance. No obligation. A free consult with an Adelaide broker who knows the local lenders.
Important information about this page

Broker services are provided at no cost to you in most cases, as we are paid a commission by the lender. Eligibility, terms, residual requirements and rates vary by lender, by asset and by individual circumstances, and are subject to change. Confirm with us before relying on any figure on this page.

This page is general information only and is not tax advice. It does not take your objectives, financial situation or needs into account. Tax treatment, effective life and deductibility depend on your circumstances, and your accountant or registered tax agent is the right person to confirm them. Loanity is a credit representative and can provide credit assistance once we understand your circumstances.