Refinance your home loan in Adelaide
with a local mortgage broker

Adelaide home values have risen faster than most of Australia since 2022, but many loans are still priced on the deposit their owners started with. We check whether yours is, compare lenders and add up the South Australian switching costs before you decide.

Four numbers for refinancing in South Australia

Two show why many Adelaide loans are worth a second look. Two are the government side of the switch.
0
Per cent rise in the mean South Australian dwelling price, June 2022 to June 2026
0
SA government fee to register your new mortgage, 2026-27
0
SA stamp duty on a refinance, abolished on mortgages from 1 July 2009
0
Our fee for arranging your refinance
Sources: ABS Total Value of Dwellings (mean dwelling price in South Australia, June 2022 and June 2026); Land Services SA Real Property (Fees) Notice 2026; Stamp Duties Act 1923 (SA), section 104. We are paid a commission by the lender when a loan settles, disclosed in writing before you commit. Lender fees can still apply.

Why refinance through a broker in Adelaide?

Refinancing a home loan in Adelaide works the same way as anywhere else, but the numbers are local: what your home is worth now, the Land Services SA fees and the lenders that serve South Australia.

We check what your equity is worth now

Rate tiers by LVR
Many lenders set a new loan’s rate from its starting LVR and keep it there. If you bought with a small deposit and your home has gone up, we show you what rate tier your loan could reach today.

We ask your lender to reprice first

Before any switch
Switching costs money, so we start with your current lender. If it moves your rate to what new customers with your equity are offered, you may not need to move at all.

We speak your language

English and Persian
Kourosh works with a large part of Adelaide’s Persian-speaking community. You can go through your loan in Persian and read the documents in English with someone explaining each part.

Your Adelaide home has probably grown. Has your rate tier?

The local reason to review a loan that is only a few years old.
The mean price of a South Australian dwelling was $669,500 in June 2022 and $979,600 in June 2026, a rise of about 46 per cent, against about 19 per cent for Australia as a whole (ABS Total Value of Dwellings). Many Adelaide owners who bought with a 5 or 10 per cent deposit now hold far more equity than when they borrowed.
That matters because lenders price loans by LVR, the loan as a share of the property value. BankSA, for example, states that rates for new loans are set on the initial LVR and do not change during the life of the loan as the LVR changes. A loan that started at 90 per cent can stay on 90 per cent pricing long after the owner has passed 60 or 70 per cent.
There are two ways to fix it. Ask your current lender to reprice the loan for your current value and balance, or refinance to a lender that prices your loan on its new valuation. Either way the lender orders a valuation, so we check the likely value with you first.

Worked example: an Adelaide purchase from 2022, four years on

A home bought in June 2022 at the mean South Australian price with a 10 per cent deposit, on a 30-year principal and interest loan.
June 2022June 2026
Home value (tracks the SA mean)$669,500$979,600
Loan balance$602,550$570,100
LVR90 per cent58 per cent
Equity$66,950$409,500

Rate cut after review or refinanceMonthly savingMonths to recover $758 of switching costs
0.25 percentage points$90About 8
0.40 percentage points$143About 5
0.60 percentage points$213About 4
Illustrative only, not offers. The loan is modelled at 6.0 per cent for the first four years and 6.5 per cent before the review, over the remaining 26 years; the rate cuts are examples. Switching costs are $408 in SA government fees (registering the new mortgage and discharging the old one) plus an assumed $350 lender discharge fee. Your home may not have tracked the SA mean, which is why a valuation comes first.

What it costs to refinance in South Australia

The government side of an Adelaide refinance is small and fixed. The lender side is where the costs vary.
CostAmount in SAWhat to know
Registering the new mortgage$204Land Services SA fee for 2026-27, set by the Real Property (Fees) Notice 2026.
Discharging the old mortgage$204Also a Land Services SA registration fee for 2026-27.
Stamp duty$0Duty on mortgages in South Australia was abolished from 1 July 2009 (Stamp Duties Act 1923, section 104).
Lender discharge feeSet by your lenderIn your loan contract. Exit fees are banned on home loans taken out since 1 July 2011.
Break costFixed rates onlyQuoted by your lender. It depends on how rates have moved since you fixed.
Application and valuationOften waivedSome lenders charge them on a refinance; ask before you apply.
LMIAbove 80 per cent LVRRare for Adelaide owners who have held their home a few years, given the price growth since 2022.
Fees are from the Land Services SA fee schedule for 2026-27 and change each financial year. Add every cost that applies to you and divide by the monthly saving to get your break-even point in months; the refinance calculator does the arithmetic.

When Adelaide homeowners refinance

Six situations we see most. The first two often need no new lender at all.

You bought with a small deposit

Bought between 2020 and 2023 with a 5 to 10 per cent deposit? Your LVR may now be far lower than when you borrowed, and your rate may still reflect the old one. Start with a repricing request.

Your fixed rate is ending

When a fixed term ends the loan rolls to the lender’s variable rate. Review it in the weeks before it ends, when no break cost applies.

You want to renovate

Equity can fund a renovation, assessed as new lending against your income. Get builder quotes first so the loan matches the real cost.

You are buying an investment property

Equity in your Adelaide home can become the deposit for an investment purchase. Lenders look at the combined debt and your income across both loans.

You have other debts

Cards, car loans and personal loans can be rolled in, but only save money if cleared on a short timeline. See debt consolidation in Adelaide.

Your situation has changed

A separation, releasing a guarantor or moving from one income to two all mean restructuring the loan, and are often a good time to compare lenders too.
We also refinance investment loans, car loans and personal loans. For the national guide to switching lenders, costs and broker duties, see refinancing your home loan.

How an Adelaide refinance works with us

Three steps, and no fee from us for arranging it.

1

Your loan and your equity, 30 minutes

In person on Prospect Road, or by phone or video. Bring your latest statement and rates notice and we estimate your LVR today.

2

Reprice or compare

We ask your current lender to reprice first, then compare other lenders on rate, fees and total cost over the years you will keep the loan.

3

Application to settlement

We lodge the application and answer the lender’s questions. The old mortgage is discharged and the new one registered with Land Services SA at settlement. Timing is set by the lenders.

What to bring to your Adelaide refinance review

With these we can estimate your LVR and compare real lenders in the first meeting.

Your home loan statement

The latest statement, the payout figure if you have it, and for a fixed rate the end date and a break cost quote.

Your council rates notice

South Australian rates notices show the Valuer-General’s capital value. It is a first check only; the lender orders its own valuation.

Proof of income

Employees: two recent payslips. Self-employed: two years of tax returns and notices of assessment, or recent BAS.

Other debts and ID

Statements for cards, car and personal loans and buy now pay later accounts, and photo ID for everyone on the loan.
Do not have all of it? Come anyway. There is no cost either way.

Refinancing across Adelaide

Homeowners we help to refinance, from the city fringe to the Fleurieu.

City and inner north

North Adelaide, Prospect, Fitzroy, Thorngate, Ovingham, Croydon, Kilkenny, Ridleyton, Brompton, Hindmarsh

Eastern suburbs

Kensington Park, Rose Park, Toorak Gardens, Erindale, Rostrevor, Athelstone, Paradise, Campbelltown, Felixstow, Hectorville

Western suburbs

Seaton, Kidman Park, Flinders Park, Lockleys, Brooklyn Park, Plympton, Novar Gardens, Glenelg North, West Beach, Largs Bay

Northern suburbs

Parafield Gardens, Paralowie, Ingle Farm, Para Hills, Wynn Vale, Greenwith, Smithfield, Andrews Farm, Blakeview, Angle Vale

Southern suburbs

Glengowrie, Warradale, Seacombe Gardens, Flagstaff Hill, Woodcroft, Reynella, Christie Downs, Port Noarlunga, Moana, Sellicks Beach

Hills and Fleurieu

Crafers, Bridgewater, Hahndorf, Woodside, Lobethal, Echunga, Meadows, McLaren Vale, Willunga, Encounter Bay
Values have not risen evenly across these suburbs, so your LVR depends on your own valuation. Plenty of clients do the whole refinance by phone and email.

Come and see us in Prospect

We work with homeowners across Adelaide, including Prospect, Walkerville, Norwood, Unley, Glenelg, Mawson Lakes, Marion and the Adelaide Hills.
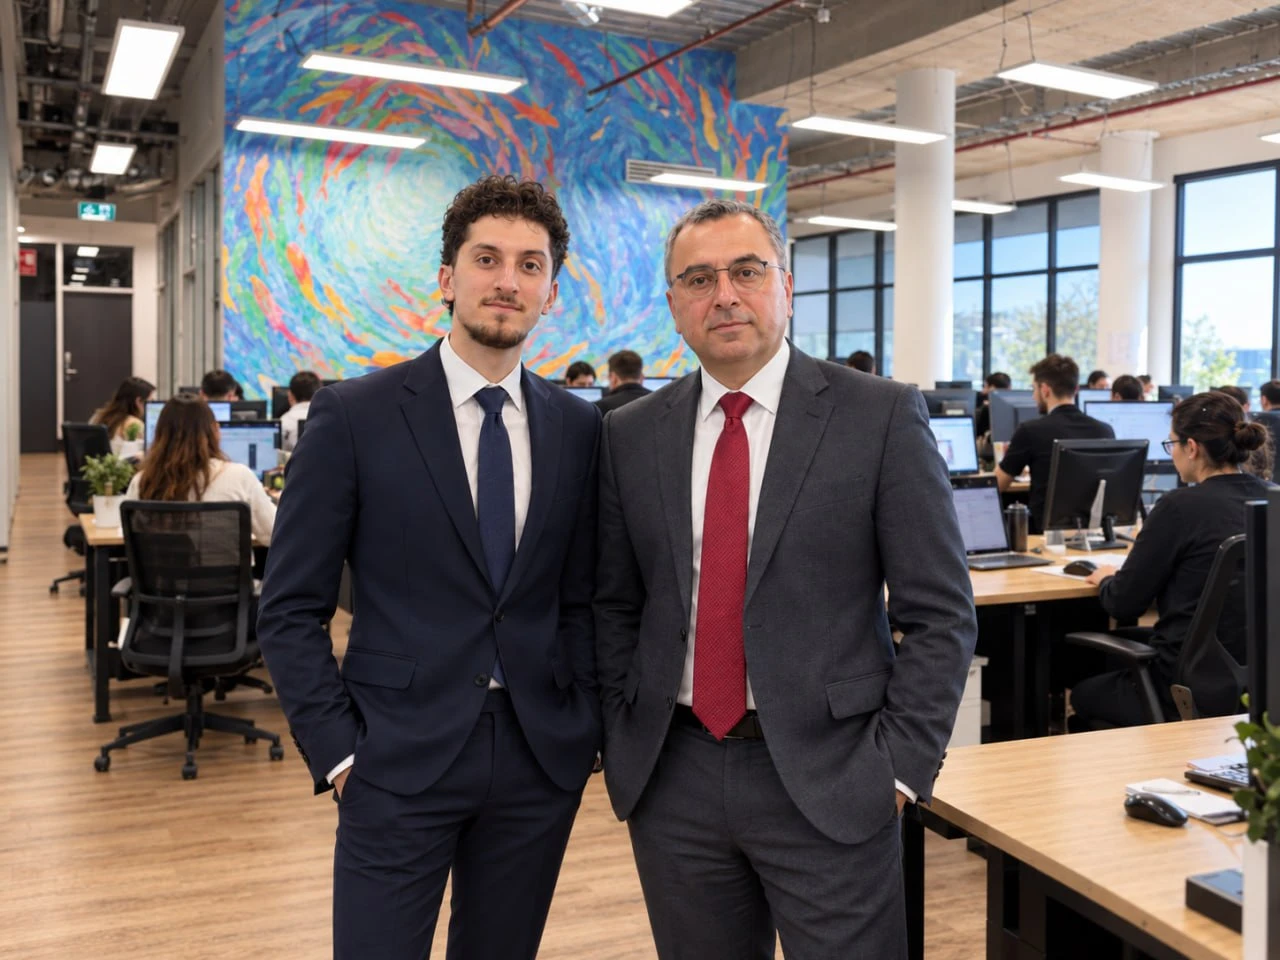
The Loanity team at the Prospect Road office in Adelaide

Call us on

1800 237 537

1/132 Prospect Rd
Prospect SA 5082

Mon to Fri 9:00am to 5:00pm
Sat 9:00am to 3:00pm, Sunday closed

We compare the lender panel for you

0
We compare 60 lenders on our panel
0
Scan through over 260 loan options 
0
Our fees disclosed up front
0
3 shortlisted options, presented to you
Judo Bank logo
Capify logo
Banjo logo
Angle Finance logo
Wisr logo
Shift logo
Plenti logo
Pepper Money logo
NOW Finance logo
Latitude logo
Lumi logo
Moula logo
Lenders available through our panel. Availability depends on the asset, the amount and your circumstances.

Related pages

The national guide refinancing your home loan covers broker versus bank, every switching cost and how brokers are paid. For buying in South Australia see home loans in Adelaide, and for other debts debt consolidation in Adelaide.
To run your own numbers, the refinance calculator shows your break-even point, the loan comparison calculator compares two loans side by side, and the extra repayment calculator shows what paying more each month does to your term.
Still got questions?

Refinancing questions from Adelaide, answered

Which bank is the best for refinancing a home loan?

There is no single best bank. Each lender prices loans differently by LVR, loan size and income type, and that changes over time. For an Adelaide owner whose home has risen in value, the useful comparison is which lender will price the loan on its current LVR, and at what total cost over the years you keep it.

Common blockers are income that no longer passes the lender’s test at a rate about 3 percentage points above the actual rate, missed repayments, a property the lender will not accept, or a loan above 80 per cent of the value without LMI. A rate review with your current lender can still be possible when a new lender says no.

Keep your repayment where it is when your rate falls, or pay extra each month. On a $570,000 loan, the saving from a lower rate left inside the loan shortens the term rather than lowering the repayment. The extra repayment calculator shows how many years a given amount removes.

Look for a broker who shows you the credit representative or licence number, explains how they are paid, compares more than one lender and asks your current lender to reprice before recommending a switch. Brokers must act in your best interests by law.

The government fees are $204 to register the new mortgage and $204 to discharge the old one in 2026-27, with no stamp duty. Add your lender’s discharge fee, any break cost on a fixed rate and any application or valuation fee from the new lender.

No. South Australia abolished duty on mortgages from 1 July 2009, and refinancing does not transfer the property, so no transfer duty applies either. You pay only the Land Services SA registration fees.

Yes, and in Adelaide that is often the main reason. A new valuation can lower your LVR into a cheaper rate tier, remove the need for LMI and free equity for other plans. Ask your current lender to reprice first, then compare.

Yes. You can ask your current lender for a rate review, which needs no application, or switch to another of its loans. Both avoid the government fees of a full refinance. If the lender will not match what new customers with your equity are offered, compare other lenders.

It depends on the new lender’s assessment, the valuation and how quickly your current lender releases the mortgage. We give you an estimate once we know the lender, but the lenders set the settlement date.

Yes. Kourosh works with a large part of Adelaide’s Persian-speaking community, and the whole conversation can happen in Persian. The loan documents are in English, and we will go through them with you.

Talk to an Adelaide refinance broker

A free 30 minute review of your loan, your equity today and whether a reprice or a refinance pays. Call 1800 237 537 or book a time that suits you.

Important information about this page

Broker services are provided at no cost to you in most cases, as we are paid a commission by the lender. Lender and government fees may apply and are set out in your loan documents. Eligibility, terms and rates vary by lender and by individual circumstances and are subject to change.
This page is general information only. It does not take your objectives, financial situation or needs into account, and it is not tax or legal advice. Property values are ABS means for South Australia and your home may differ; the worked example uses illustrative rates, not offers. Fees are Land Services SA 2026-27 and change each financial year. Last updated 17 October 2026. Loanity is a credit representative and can provide credit assistance once we understand your circumstances. Green Idea Pty Ltd, Credit Representative Number 576678, is an authorised representative of Red Rock Brokers Group Pty Ltd, Australian Credit Licence 405961.