Business loan broker in Adelaide
matched to how you get paid

We compare bank, non-bank and online lenders for Adelaide businesses, match the loan to when your money actually comes in, and show you the security, guarantees and total cost before you sign.

Four numbers to know before you borrow in SA

Two are South Australian rules most loan pages never mention. One is your safety net if something goes wrong. One is our fee.
0
Stamp duty on goodwill and equipment when you buy an SA business
0
Stamp duty on commercial premises (qualifying land) in SA
0
Million: the largest small business loan AFCA can consider
0
Our fee for arranging your business loan
We are paid a commission by the lender when a loan settles, and that is disclosed to you in writing before you commit. Lender fees, legal costs, registration fees and GST can still apply. Stamp duty figures are from RevenueSA Information Circulars 76 and 103, and the AFCA limit is from AFCA.

Why a broker rather than going straight to an online lender?

The Adelaide search results for business loans are mostly online lenders and banks, each showing its own products. Here is what is different about coming to us.

We compare banks and online lenders

Bank, non-bank and online
Online lenders sell speed. Banks usually cost less but take longer and want security. We put both side by side with the total cost and the repayment frequency, so if you choose speed, you choose it knowing the price.

We check who you would be signing with

AFCA membership check
A lender that lends only for business purposes does not need an Australian credit licence. Before you sign, we confirm the lender is a member of AFCA, so you have a free, independent complaints service if something goes wrong.

We speak your language

English and Persian
Kourosh works with a large part of Adelaide’s Persian-speaking community. You can talk through your figures in Persian and read the loan documents in English with someone explaining each part.

Match the loan to how your business gets paid

Six cash cycles we see in Adelaide businesses, and the type of finance that usually fits each one.

Paid on 30 to 90 day invoices

Trade subcontractors, wholesalers and suppliers to the defence and shipbuilding work around Osborne and Edinburgh often wait weeks to be paid for finished work. Invoice finance advances money against those unpaid invoices, so the cost is tied to the invoices you are waiting on rather than running all year.

Paid once a season

Wineries in the Barossa, McLaren Vale and the Clare Valley, growers and tourism operators earn most of their income in a few months. A line of credit or an overdraft lets you draw in the lean months and repay when the season pays. Interest is charged on what you draw, usually plus a fee on the limit.

Paid every day

Cafes, shops, salons and trades with steady card takings often suit a term loan with regular repayments for a fit-out or expansion. Some online lenders collect repayments daily or weekly, so check the repayment frequency against your cash flow, not just the amount.

Buying your premises

Since 1 July 2018 South Australia has charged no stamp duty on transfers of non-residential, non-primary production land (RevenueSA Information Circular 103), so the cash you need at settlement is mainly the deposit and costs. Commercial property loans usually need a larger deposit and a shorter term than a home loan.

Buying a business

Since 18 June 2015 SA has charged no stamp duty on goodwill, plant and equipment not fixed to land, or intellectual property (RevenueSA Information Circular 76). Lenders look closely at the business’s trading history and your own experience in the industry, and often ask for property as security.

New ABN or no recent tax returns

Some lenders accept BAS statements, business bank statements or an accountant’s declaration instead of full financials, usually at a higher cost and for a smaller amount. Our national business loans page covers low doc loans and borrowing with an ABN in detail.
Buying a vehicle, machine or tools? That is asset finance, and it has its own page: equipment finance in Adelaide.

How a business loan is secured, and what it usually means for you

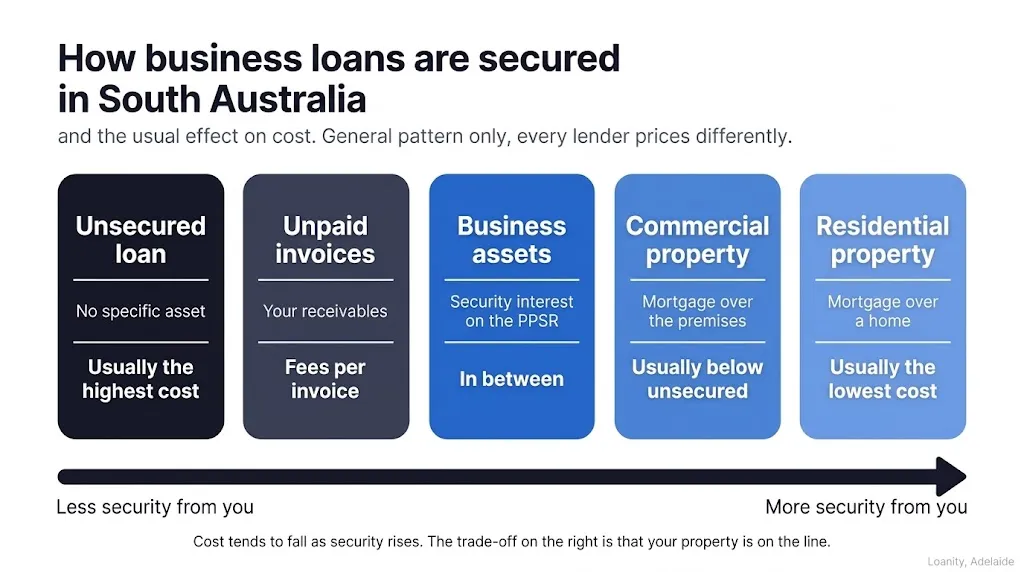
Five ways lenders secure business lending in South Australia. In general, the less security you offer, the higher the cost.
Unsecured loanUnpaid invoicesBusiness assetsCommercial propertyResidential property
What the lender holdsNo specific assetYour receivables, the money customers owe youA security interest over the business’s present and future assetsA mortgage over the premisesA mortgage over a home, yours or a guarantor’s
Where it is registeredSome lenders still register a security interest on the PPSRPersonal Property Securities Register (PPSR)Personal Property Securities Register (PPSR)SA Lands Titles OfficeSA Lands Titles Office
Personal guaranteeUsually asked of directorsOften asked of directorsOften asked of directorsUsually asked of directorsThe property owner signs the mortgage
Usual cost compared with the othersUsually the highestFees per invoice, depends on your customersIn betweenUsually below unsecuredUsually the lowest
Check before you signRepayment frequency and the total cost, not just the repaymentWhether your customers are told about the arrangementWhat the security stops you doing later, such as borrowing elsewhereDeposit, term and any lease the valuer will rely onYour home is at risk if the business cannot pay
How Adelaide business loans are secured and the usual effect on cost - Loanity
General description only, not a quote or an offer. Each lender sets its own security, guarantee and pricing rules, and they change over time. Mortgages over land in South Australia are registered with the Lands Titles Office, and security over other business assets is registered on the PPSR.

What changes when the loan is for your business

The part most loan pages leave out. Worth reading before you sign anything.
Credit used wholly or predominantly for business purposes is generally not covered by the National Credit Code. Protections built for home and personal loans, such as the Code’s hardship provisions and the responsible lending rules, may not apply. Lenders usually ask you to sign a business purpose declaration. Read it carefully, because it records that the money is for your business.
Many business lenders ask directors to sign a personal guarantee, and many register a security interest over the business’s assets on the PPSR. If your home is offered as security, the loan is secured against it even though the money is for the business, so the risk to the home is real.
If something goes wrong, AFCA can consider complaints from small businesses with fewer than 100 employees about credit facilities of up to $5 million, provided the lender is an AFCA member. Farmers in South Australia have one more protection: under the Farm Debt Mediation Act 2018, a creditor must offer mediation through the Small Business Commissioner before enforcing a farm mortgage.

What to bring to the first appointment

With these we can show you realistic lenders in the first conversation.

ABN, structure and ID

Your ABN, plus the ACN for a company or the trust deed for a trust. Photo ID for every director, partner or trustee who will sign the loan or a guarantee.

Trading figures

Recent BAS statements, your last two years of financial statements and tax returns if you have them, and three to six months of business bank statements. Lenders vary in what they need.

What the money is for

A quote, a list of unpaid invoices or a cash flow forecast. For a purchase, the business sale contract or the property contract, and for premises any existing lease.

Current debts and tax

Statements for existing business loans, cards and leases, and your ATO account balance including any payment plan. Tax debt changes which lenders will look at you, so it is better on the table from the start.
Do not have all of it? Come anyway. The first meeting is often where the list gets written, and there is no cost either way.

How it works

Three steps, and no fee from us for arranging your business loan.

1

Map how your business gets paid, 30 minutes

In person on Prospect Road, or by phone or video. We look at when money comes in and goes out, what the loan is for, and what security you can offer or would rather keep out of it.

2

Compare lenders and structures

We show you bank, non-bank and online options side by side: total cost, repayment frequency, security and personal guarantees for each. We also confirm each lender is an AFCA member.

3

Application, approval and settlement

We prepare and lodge the application and answer the lender’s credit questions. Approval and timing are decided by the lender, and we keep you updated until the funds are released.

Business finance across Adelaide and SA

From the CBD and the industrial north to the wine regions.

City and fringe

Adelaide CBD, North Adelaide, Kent Town, Thebarton, Mile End, Keswick, Parkside, Unley

Inner north

Prospect, Kilburn, Regency Park, Wingfield, Dry Creek, Gepps Cross, Enfield, Blair Athol

West and port

Port Adelaide, Osborne, Gillman, Ottoway, Hindmarsh, Woodville, Findon, Netley

North

Edinburgh, Elizabeth, Salisbury, Mawson Lakes, Parafield, Burton, Direk, Gawler

South

Lonsdale, Tonsley, Edwardstown, Melrose Park, Marion, Morphett Vale, Noarlunga, Seaford

Regions

Barossa Valley, Clare Valley, McLaren Vale, Adelaide Hills, Mount Barker, Murray Bridge, Victor Harbor
Your postcode does not change what a lender will do, but a broker who understands how a vintage, a defence contract or a building job gets paid can explain your cash flow to a lender in its own terms. Plenty of clients still do the whole thing by phone and email.

Come and see us in Prospect

We work with businesses across Adelaide, including Prospect, Kilburn, Regency Park, Wingfield, Port Adelaide, the CBD, Edinburgh and Lonsdale, and with clients in the Barossa and across regional South Australia.
The Loanity team at the Prospect Road office in Adelaide

Call us on

1800 237 537

1/132 Prospect Rd
Prospect SA 5082

Mon to Fri 9:00am to 5:00pm
Sat 9:00am to 3:00pm, Sunday closed

We compare the lender panel for you

0
We compare 60 lenders on our panel
0
Scan through over 260 loan options 
0
Our fees disclosed up front*
0
3 shortlisted options, presented to you
Judo Bank logo
Capify logo
Banjo logo
Angle Finance logo
Wisr logo
Shift logo
Plenti logo
Pepper Money logo
NOW Finance logo
Latitude logo
Lumi logo
Moula logo
Lenders available through our panel. Availability depends on the asset, the amount and your circumstances.

Other things we handle

Our national business loans page covers low doc loans, borrowing with an ABN, finance for ATO tax debt and business debt consolidation. Equipment finance in Adelaide covers vehicles, machinery and tools, and if the debts are personal rather than business, see debt consolidation in Adelaide. Buying or refinancing a home is covered on home loans in Adelaide.
To run your own numbers, the asset finance calculator estimates repayments on equipment, the loan comparison calculator compares the total cost of two loans, and the comparison rate calculator shows what fees do to a quoted rate.
Still got questions?

Business loan questions from Adelaide, answered

Do mortgage brokers do business loans?

Many do, and we do. From our Prospect office we arrange secured and unsecured business loans, low doc loans, lines of credit and overdrafts, invoice finance and commercial property loans, as well as home loans. Equipment and vehicle finance has its own page.

From banks, from non-bank and online lenders, or through a broker who compares them. The Adelaide search results are mostly online lenders and banks, each showing only its own products. A broker can put several lenders side by side for your business and the security you can offer.

It depends mostly on trading history, profit, security and your credit history. A business with two years of financials and property to offer has the widest choice. Newer businesses and those without security still have options, usually at a higher cost and for smaller amounts.

Unsecured online loans usually ask for the fewest documents and decide fastest, which is why they lead the search results. They also usually cost the most, and some collect repayments daily or weekly. Easiest is not the same as best value, so compare the total cost before you choose speed.

There is no single answer. Each lender has its own appetite for industries, loan sizes, security and trading history, and that changes over time. The useful question is which lender fits your business now, and that is what a broker comparison is for.

No lender approves easily across the board. Banks usually want trading history and security, while non-bank and online lenders accept more risk at a higher price. We tell you which lenders are realistic before any application goes in, so you do not collect unnecessary credit enquiries.

The main types are term loans, secured or unsecured, lines of credit and overdrafts, invoice finance, commercial property loans, equipment and asset finance, and low doc loans for businesses without full financials. The table above shows how each is usually secured.

Not on qualifying land. RevenueSA states that no stamp duty arises on a transfer of non-residential, non-primary production land under a contract entered into on or after 1 July 2018. Residential and primary production land is still dutiable, and GST and other costs can apply, so confirm your purchase with your conveyancer or accountant.

Not on the business assets. Since 18 June 2015 SA has charged no stamp duty on transfers of non-real property, which includes goodwill, plant and equipment not fixed to land, and intellectual property. If the purchase includes land, the land is assessed separately under the commercial property rule above.

Yes. Kourosh works with a large part of Adelaide’s Persian-speaking community, and the whole conversation can happen in Persian. The loan documents are in English, and we will go through them with you.

Talk to an Adelaide business finance broker

A free 30 minute conversation about how your business gets paid, what the loan is for and which lenders fit. Call 1800 237 537 or book a time that suits you.

Important information about this page

Broker services are provided at no cost to you in most cases, as we are paid a commission by the lender. Lender and government fees may apply and are set out in your loan documents. Eligibility, terms and rates vary by lender and by individual circumstances and are subject to change.
This page is general information only. It does not take your objectives, financial situation or needs into account, and it is not tax or legal advice. Stamp duty, AFCA and farm debt mediation are summarised from RevenueSA, AFCA and the Small Business Commissioner as at October 2026 and can change. Loanity is a credit representative and can provide credit assistance once we understand your circumstances. Green Idea Pty Ltd, Credit Representative Number 576678, is an authorised representative of Red Rock Brokers Group Pty Ltd, Australian Credit Licence 405961.