Debt consolidation in Adelaide
through a local mortgage broker

We refinance credit cards, personal loans, car loans and buy now pay later into one loan, and we show you the total cost of each option before you sign, not just the lower repayment.

One $40,000 debt, four ways to repay it

From the worked example further down this page. The structure matters more than the rate.
0
Months to clear it at the old repayment
0
Years if it is simply added to the mortgage
0
Repayment instead of three
0
Cost to you for arranging the refinance
We are paid a commission by the lender when a loan settles, and that is disclosed to you in writing before you commit. Lender and government fees can still apply and are set out in your loan documents.

Why a mortgage broker rather than a debt consolidation company?

Moneysmart and consumer legal services both warn about debt consolidation companies. Here is what is different about using a broker.

We arrange loans, we do not manage your debt

Credit representative
We do not take your money, negotiate with your creditors or put you into a debt agreement. We find a lender and arrange a new loan, and at settlement that loan is used to pay out the old ones. Our credit representative and licence details are at the bottom of this page.

We refinance every kind of loan

Home, personal, car, cards
Some debts belong inside a home loan, some are better on a personal consolidation loan, and some are better left alone. Because we can refinance all of them, we are not pushed toward one answer, and you see the options side by side.

We speak your language

English and Persian
Kourosh works with a large part of Adelaide’s Persian-speaking community. Debt is stressful enough in your first language, so you can have the whole conversation in Persian and read the loan documents in English with someone explaining them.

What we can consolidate, and what to leave out

Six debts we see most often in Adelaide, and how lenders usually treat each one.

Credit cards

Usually the most expensive debt in the mix and the first to clear. Lenders assess the full card limit rather than the balance, so many will ask for the card to be closed or the limit reduced once it is paid out.

Personal loans

Check the payout figure and any early repayment fee first. A personal loan with only a few months left may not be worth refinancing at all, because resetting it over a longer term adds interest for no real gain.

Car loans

A car loan can be paid out and the car released from the lender’s security. If there is a balloon payment at the end, it has to be counted in the payout, and some fixed car loans charge a fee for paying out early.

Buy now pay later

Since 10 June 2025, buy now pay later contracts are regulated as credit in Australia, and lenders look at them when they assess you. Several small balances across different apps can affect an application more than people expect.

HECS-HELP

Usually best left alone. A HELP debt is indexed rather than charged interest, and repayments come out through the tax system, so moving it into a loan that charges interest rarely makes sense. Lenders still count the repayment when they assess you.

Tax debt

Whether an ATO debt can be refinanced depends heavily on the lender and on your tax affairs being up to date. Treat it as a specialist case and mention it in the first conversation, before anything is lodged.
Whichever mix you have, the useful first step is the same: a list of every debt, with the payout figure and monthly repayment for each. Our borrowing power calculator will give you a rough idea of where you stand before you speak to anyone.

Same $40,000, four very different bills

An Adelaide household with a credit card, a car loan and a personal loan. The only thing that changes is how the debt is restructured.
Change nothingAdded to a 25-year home loanHome loan split, old repayment keptPersonal consolidation loan, 5 years
Monthly repayment$1,189$270$1,189$870
Debt cleared in4 years25 years38 months5 years
Total interest$10,610$41,025$4,278$12,182
Compared with changing nothingBaseline$30,415 more$6,332 less$1,572 more
What secures the debtThe car onlyYour homeYour homeNothing, it is unsecured
Total interest on the same $40,000 debt under four repayment structures
Illustrative figures, not current offers. Card $12,000 at 20 per cent, paying $400 a month. Car loan $18,000 at 9.5 per cent with 48 months left. Personal loan $10,000 at 13 per cent with 36 months left. Home loan at 6.5 per cent, close to the average owner-occupier variable rate after the Reserve Bank lifted the cash rate to 4.60 per cent on 29 September 2026. Personal consolidation loan at 11 per cent over five years. Fees, break costs and any lenders mortgage insurance are not included. Calculated by Loanity.

Home loan or personal loan consolidation?

The part of the table most people miss, and the question to settle before anything else.
Rolling debts into a home loan usually gets a lower rate than cards or personal loans, but it turns unsecured debt into debt secured by your home. Moneysmart warns that if you cannot keep up the repayments, the asset you put up as security may be at risk. If the extra borrowing takes you above 80 per cent of the property’s value, lenders mortgage insurance may also apply, which can wipe out the saving.
A personal consolidation loan keeps your home out of it but usually costs more, and as the table shows, a five-year term can cost more than keeping your current loans. The structure that tends to keep the saving is a separate split on the home loan with a short term, or with the old repayment kept, so the debt is gone in years rather than decades. Moneysmart’s guide to debt consolidation and refinancing covers the same trade-offs.
If you are already behind on repayments, talk to a free financial counsellor before you talk to any lender, including us. The National Debt Helpline is on 1800 007 007 and the Affordable SA Helpline is on 1800 025 539. Your current lenders also have hardship teams that may be able to change or pause repayments.

What to bring to the first appointment

With these we can model your actual numbers in the first conversation, the same way as the table above.

A list of every debt

Every credit card, personal loan, car loan, buy now pay later account and tax debt, with the balance, limit, monthly repayment and interest rate. A screenshot of each statement or app is fine.

Payout figures

Ask each lender for a payout figure, which can differ from the balance on your statement. Note any early repayment or break fees, and any balloon on a car loan.

Proof of income

Employees: two recent payslips. Self-employed: two years of tax returns and notices of assessment, or recent BAS if your lender will use them. Add rental statements or Centrelink letters if they apply.

Your home loan details

Your latest home loan statement and, if you have one, a recent estimate of the property’s value. This decides how much room there is to consolidate and whether lenders mortgage insurance would come into it.
Do not have all of it? Come anyway. The first meeting is often where the list gets written, and there is no cost either way.

How it works

Three steps, and no cost to you for arranging the refinance.

1

Map every debt, 30 minutes

In person on Prospect Road, or by phone or video. We list each debt with its payout and repayment, and work out what consolidating would actually save, including the cases where the honest answer is not to. Nothing is submitted anywhere at this stage.

2

Compare structures and lenders

We show you the options side by side: a home loan split, a personal consolidation loan, or leaving some debts out. Each one comes with its repayment, its term and its total interest. You choose, not us.

3

Payouts, settlement and closing old accounts

We prepare and lodge the application and deal with the lender’s questions. At settlement the new loan is used to pay out each debt, and we help you close or reduce the old accounts so the limits do not count against you next time.

Debt consolidation across Adelaide

All of metropolitan Adelaide, plus the Hills and the south coast.

Inner north

Prospect, Nailsworth, Sefton Park, Broadview, Enfield, Kilburn, Blair Athol, Collinswood, Walkerville, Medindie, Gilberton, North Adelaide

East and inner south

Norwood, Kensington, Payneham, St Peters, Unley, Malvern, Mitcham, Glenside, Burnside, Magill

West and coast

Woodville, Findon, Athol Park, Fulham, Henley Beach, Grange, West Lakes, Semaphore, Port Adelaide, Glenelg, Somerton Park, Brighton

North and outer

Mawson Lakes, Golden Grove, Modbury, Redwood Park, Salisbury, Elizabeth, Gawler, Munno Para, Tea Tree Gully

South

Marion, Oaklands Park, Morphett Vale, Aberfoyle Park, Happy Valley, Noarlunga, Seaford, Aldinga, Hallett Cove

Hills and beyond

Stirling, Aldgate, Lenswood, Mount Barker, Littlehampton, Nairne, Strathalbyn, Victor Harbor, Goolwa
Your suburb does not change what a lender will do, but sitting down with someone local can make a hard conversation about debt a little easier. Plenty of clients still do the whole thing by phone and email.

Come and see us in Prospect

We work with clients across Adelaide, including Prospect, Collinswood, Sefton Park, North Adelaide, Walkerville, Norwood, Port Adelaide, West Lakes, Henley Beach, Somerton Park and Oaklands Park, and right across the metro area.
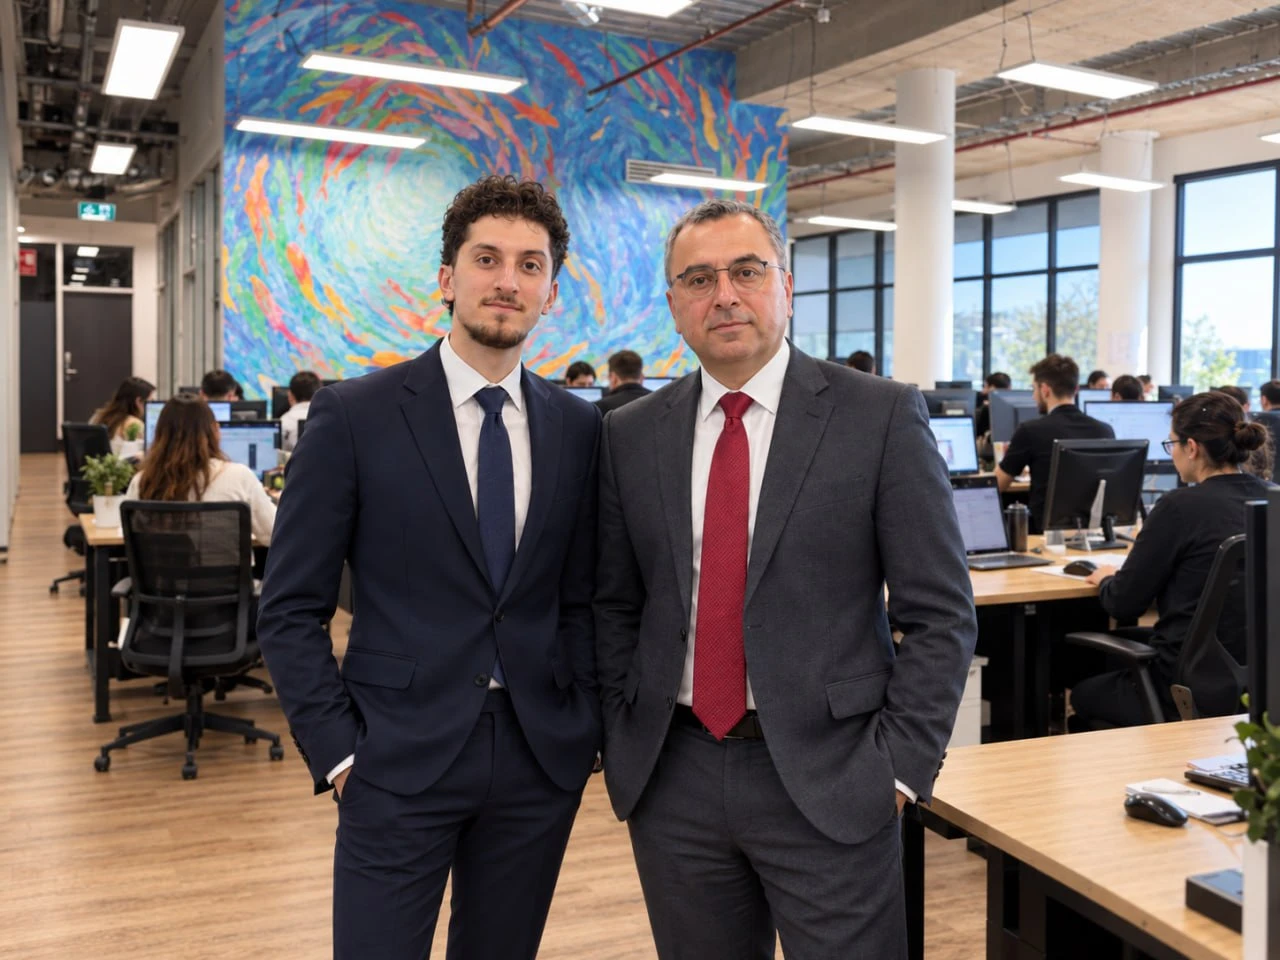
The Loanity team at the Prospect Road office in Adelaide

Call us on

1800 237 537

1/132 Prospect Rd
Prospect SA 5082

Mon to Fri 9:00am to 5:00pm
Sat 9:00am to 3:00pm, Sunday closed

We compare the lender panel for you

0
We compare 60 lenders on our panel
0
Scan through over 260 loan options 
0
Our fees disclosed up front*
0
3 shortlisted options, presented to you
Judo Bank logo
Capify logo
Banjo logo
Angle Finance logo
Wisr logo
Shift logo
Plenti logo
Pepper Money logo
NOW Finance logo
Latitude logo
Lumi logo
Moula logo
Lenders available through our panel. Availability depends on the asset, the amount and your circumstances.

Other things we handle

If you are buying or refinancing a home, our home loans in Adelaide page covers the local picture, including SA grants and HomeStart. Refinancing an existing loan covers rate reviews and equity release, and personal loans covers unsecured borrowing on its own.
To run your own numbers, the credit card calculator shows how long a balance takes to clear, the extra repayment calculator shows what keeping a higher repayment saves, and the budget planner shows the surplus a lender will look at.
Still got questions?

Debt consolidation questions, answered

Does it cost anything to use a broker for debt consolidation?

In most cases no. We are paid a commission by the lender when the loan settles, and that is disclosed to you in writing before you commit. Lender fees, discharge fees on the old loans and any break costs can still apply, and they are set out before you sign.

It can be, if the debt is cleared on a short timeline. Added to a 25-year loan, the same debt can cost several times more in interest even at a lower rate, and it becomes secured by your home. Keeping a separate split with the old repayment is how most of the saving is kept.

Each application is recorded on your credit file as an enquiry, which is why we do not send an application to a lender whose policy is unlikely to fit. Once the old debts are paid out and closed, fewer accounts and lower limits generally help future applications.

Yes, with an unsecured personal consolidation loan. The rate is usually higher than a home loan, so compare the total interest as well as the repayment. In our worked example, a five-year personal consolidation loan cost more than keeping the existing loans.

Sometimes. Specialist lenders consider borrowers with past defaults or missed payments, usually at a higher cost. If you are behind right now, a free financial counsellor on 1800 007 007 is the better first call, because a new loan will not fix a budget that does not balance.

Yes. Since 10 June 2025 buy now pay later is regulated as credit, and lenders consider it when they assess you. Clearing several small balances and closing the accounts can tidy up your position before a home loan application.

Debt consolidation is a new loan that pays your existing debts out in full. A debt agreement is a formal arrangement under the Bankruptcy Act that can reduce what you repay, but it is recorded on the National Personal Insolvency Index and on your credit file. They are very different, and a debt agreement should only be considered after speaking with a free financial counsellor.

It depends on the rates, the payout costs and above all the term. In our example the same $40,000 cost $4,278 in interest on a home loan split with the old repayment kept, and $41,025 when it was added to a 25-year loan. We model your own figures before you decide.

It depends on the lender and on how quickly payout figures come back from your current lenders. Refinancing onto a home loan involves a valuation and a settlement, so it generally takes longer than a personal loan. Approval timing is the lender’s decision, not ours.

Yes. Kourosh works with a large part of Adelaide’s Persian-speaking community and the whole conversation can happen in Persian. The loan documents are in English, and we will go through them with you.

Talk to an Adelaide broker about your debts

A free 30 minute review of every debt you have, with the total cost of each option in front of you. Call 1800 237 537 or book a time that suits you.

Important information about this page

Broker services are provided at no cost to you in most cases, as we are paid a commission by the lender. Lender and government fees may apply and are set out in your loan documents. Eligibility, terms and rates vary by lender and by individual circumstances and are subject to change.
This page is general information only. It does not take your objectives, financial situation or needs into account, and it is not tax or legal advice. Worked examples on this page are illustrative and use assumed rates, not current offers. Loanity is a credit representative and can provide credit assistance once we understand your circumstances. Green Idea Pty Ltd, Credit Representative Number 576678, is an authorised representative of Red Rock Brokers Group Pty Ltd, Australian Credit Licence 405961.