Personal loan broker
in Adelaide

Search for a personal loan broker in Adelaide and you will be promised approval in 24 to 48 hours, sometimes the same day. No broker controls that. This page explains what actually decides how fast a personal loan is approved, and the part a broker can genuinely change.

One application, not six

Our office is on Prospect Road, about ten minutes from the Adelaide CBD. What a broker is worth here is not a secret rate. It is not collecting declines around town while you work out who lends to someone in your position.
0
Lenders on our panel
0
Loan products we can compare
0
Credit enquiry, not six
0
Cost to you for arranging your finance
The lender pays us a commission when a loan settles, and we disclose that to you in writing before you commit to anything. Lender fees and government charges can still apply, and they are set out in your loan documents.

What an Adelaide broker can promise you, and what nobody can

Read the promises on the first page of results carefully. Most of them are not the broker’s to make.
Approval is the lender’s decision, not the broker’s. A licensee has to assess whether the loan is unsuitable for you before it can be offered, which means verifying your income, your expenses and your existing commitments. That assessment takes as long as the lender’s queue and your paperwork make it take. Anyone naming a fixed number of hours before they have seen your file is describing a hope, not a process.
What a broker genuinely changes is narrower, and more useful: which lender sees your file at all, how complete it is on the day it lands, and whether it goes somewhere the policy actually fits. That is usually the difference between one enquiry and four.

What we will not tell you

We will not put a number of hours on a decision, because the timing sits with the lender. We will not suggest the answer is likely to be yes regardless of your credit history. And we will not quote you a rate before we have looked at your situation, because a rate quoted blind is just the advertised one.

What actually moves the timeline

Whether your documents are complete on day one. Whether your income is salaried, casual, self-employed or a mix. Whether anything on your credit file needs explaining. Whether the loan is secured, which adds a valuation step. And the lender’s own queue that week, which nobody outside the lender can see.

Where being local helps

You can sit down with the person handling your file rather than being passed around a queue, and we can go through the documents together before anything is lodged. That does not make a lender faster. It does stop the week lost to a file that went in incomplete.

If an Adelaide lender has already said no

The worst next move is applying to whoever is next on the list.
A decline is one lender’s policy meeting your circumstances on one day. It is not the market’s answer, and the decline itself is not recorded on your credit file. The enquiry is, and a run of enquiries in a short window is visible to every lender you approach afterwards. That is the real cost of working down a list.

Find out why first

Was it the income type, the credit limits you already hold, something listed on the file, or simply the amount against the term? Each has a different fix, and some take a few months rather than a few days.

Check the file itself

Errors are more common than people expect, and a listing that should not be there can be disputed. If the file needs work before it will carry an application, our credit check and repair page covers how that works.

Then pick the lender deliberately

Specialist lenders write business the major banks will not, on different terms. Whether that trade is worth making depends on the amount, the purpose and how long you need it for. If the debt is spread across cards and personal loans, the better question may not be another personal loan at all: see debt consolidation in Adelaide.
If anyone tells you the answer will be yes regardless of your history, be careful. Nobody can promise that in advance, and a credit licensee is required to assess whether a loan is unsuitable for you before offering it.

When you need a broker, and when you do not

Most pages selling broker services will not write the first half of this.

Go direct, honestly

Stable salary, clean credit file, a modest amount, and your own bank has a competitive offer? You may not need us. Compare on the comparison rate rather than the headline rate, read the fee schedule, and apply. We would rather tell you that than take an application that was never going to be worth our involvement.

Call a broker instead

Casual, contract or self-employed income. More than one existing debt. Anything on the credit file that needs explaining. A recent decline. An amount large enough that the structure matters. Or simply no appetite for working out which of sixty lenders would consider you.

Why the second list matters

Those are the files where picking the wrong lender costs a real enquiry and several weeks, and where the gap between lenders is widest. That is where the work earns its place.
Everything on this page is about getting the application right rather than getting it fast. The national personal loans page covers the product side in more detail: secured against unsecured, how the comparison rate works, the fees that decide the real cost, and how much you can borrow. If the borrowing is tied to property, start at home loans in Adelaide instead.

How it works

Three steps, and no cost to you for arranging the finance.

1

Sit down with us, 30 minutes

In the Prospect office or on a call, whichever suits. We go through the amount, the purpose, your income type and anything on the file that needs explaining.

2

We shortlist before anything is lodged

We match your circumstances against lender policy first, then look at pricing among the lenders that would realistically take the file. You see the options side by side and you choose. Nothing is submitted until you say so.

3

Application through to settlement

We prepare it, lodge it, answer the lender’s questions and keep you posted. If something is going to be a problem you hear it early, not as a decline three weeks later.

Come and see us in Prospect

We work with clients across Adelaide, including Prospect, Collinswood, Sefton Park, North Adelaide, Walkerville, Norwood, Port Adelaide, West Lakes, Henley Beach, Somerton Park and Oaklands Park, and right across the metro area.
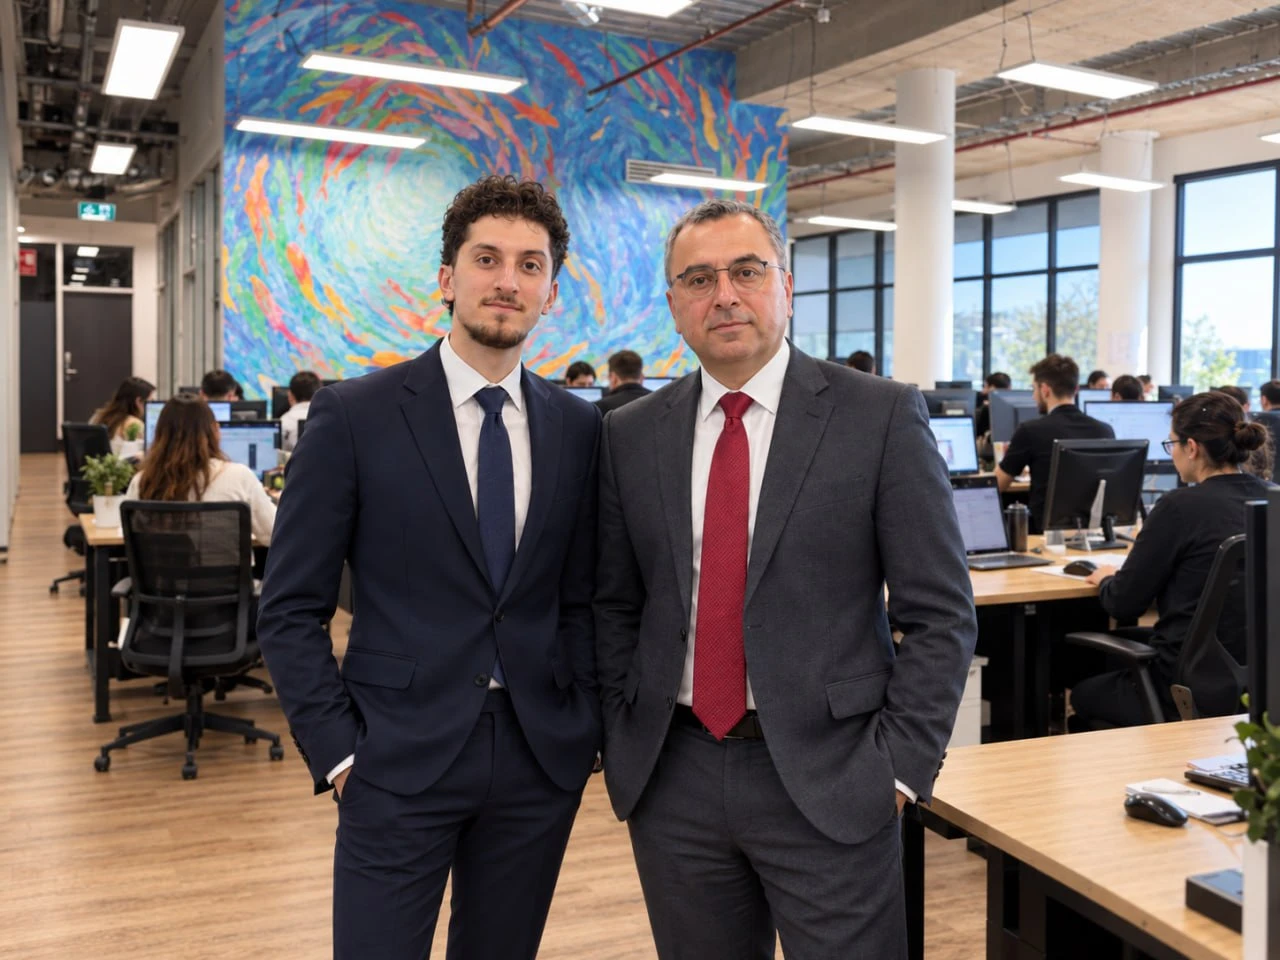
The Loanity team at the Prospect Road office in Adelaide

Call us on

1800 237 537

1/132 Prospect Rd
Prospect SA 5082

Mon to Fri 9:00am to 5:00pm
Sat 9:00am to 3:00pm, Sunday closed

We compare the lender panel for you

0
We compare 60 lenders on our panel
0
Scan through over 260 loan options 
0
Our fees disclosed up front*
0
3 shortlisted options, presented to you
Judo Bank logo
Capify logo
Banjo logo
Angle Finance logo
Wisr logo
Shift logo
Plenti logo
Pepper Money logo
NOW Finance logo
Latitude logo
Lumi logo
Moula logo
Lenders available through our panel. Availability depends on the asset, the amount and your circumstances.
Still got questions?

Personal loan questions, answered

What does a personal loan broker in Adelaide actually do?

We read your income, your existing commitments and your credit position against the credit policy of the lenders on our panel, shortlist the ones that would realistically take the file, and show you the options side by side. Then we prepare and lodge the application and stay with it through to settlement. The decision stays with the lender.

In most cases no. The lender pays us a commission when a loan settles, and we disclose that to you in writing before you commit. Lender fees and government charges can still apply and are set out in your loan documents.

Honestly, it depends, and anyone naming a fixed number of hours before seeing your file is guessing. A credit licensee has to verify your income, your expenses and your existing commitments and assess whether the loan is unsuitable for you before it can be offered. What moves the timeline is whether your documents are complete on day one, your income type, anything on the credit file that needs explaining, whether a valuation is involved, and the lender’s own queue that week. A complete file sent to the right lender is the fastest version of this, and that part we can help with.

Because the rate you would actually be offered depends on your credit file, your income and the lender, so a number printed here would be marketing rather than information. We quote once we have looked at your situation, and you see the comparison rate alongside the interest rate so the fees are in the figure.

Usually, and which lender you approach matters more than anything else. Lenders differ a lot on how they treat business income, how long the ABN has been trading and what evidence they will accept. Some want two years of returns, others will look at BAS statements or an accountant’s letter. Picking the wrong one first costs you an enquiry.

Each application is recorded as an enquiry on your credit file, and several enquiries in a short window are visible to every lender you approach afterwards. That is the practical argument for working out where you fit before applying, rather than trying lenders one at a time.

Sometimes, and the honest answer turns on the term. Consolidation usually lowers the monthly repayment, and it can raise the total interest if a short debt is stretched over a long one. We worked this through with real figures on our debt consolidation in Adelaide page, including the case where consolidating costs more than doing nothing.

Often, but not by applying to the next lender on a list. A decline reflects one lender’s policy meeting your circumstances on one day. Find out which part caused it, check the credit file for errors, then choose the next lender deliberately rather than alphabetically.

Tell the lender early rather than late. Under Australian credit law you can ask your lender for a hardship arrangement, and lenders have a process for it. Free financial counselling is available on the National Debt Helpline on 1800 007 007.

Find out where you stand

A free 30 minute conversation, no obligation, and nothing lodged anywhere until you say so. In the Prospect office or on a call, whichever suits.

Important information about this page

This page is general information only and does not take your objectives, financial situation or needs into account. It is not credit assistance and it is not a quote. Approval, the amount, the rate and the timeframe are decided by the lender, not by us, and a credit licensee must assess whether a loan is unsuitable for you before it can be offered. We are paid a commission by the lender when a loan settles, disclosed to you in writing before you commit. Lender fees and government charges may apply. Nothing here is a promise of approval, of a rate, or of a timeframe. Checked 9 October 2026.
Loanity is a finance broker, not a lender. We do not decide applications.